
Coupling compliance and voluntary carbon markets: a system dynamics assessment in China
 0
Graphical Abstract
Abstract
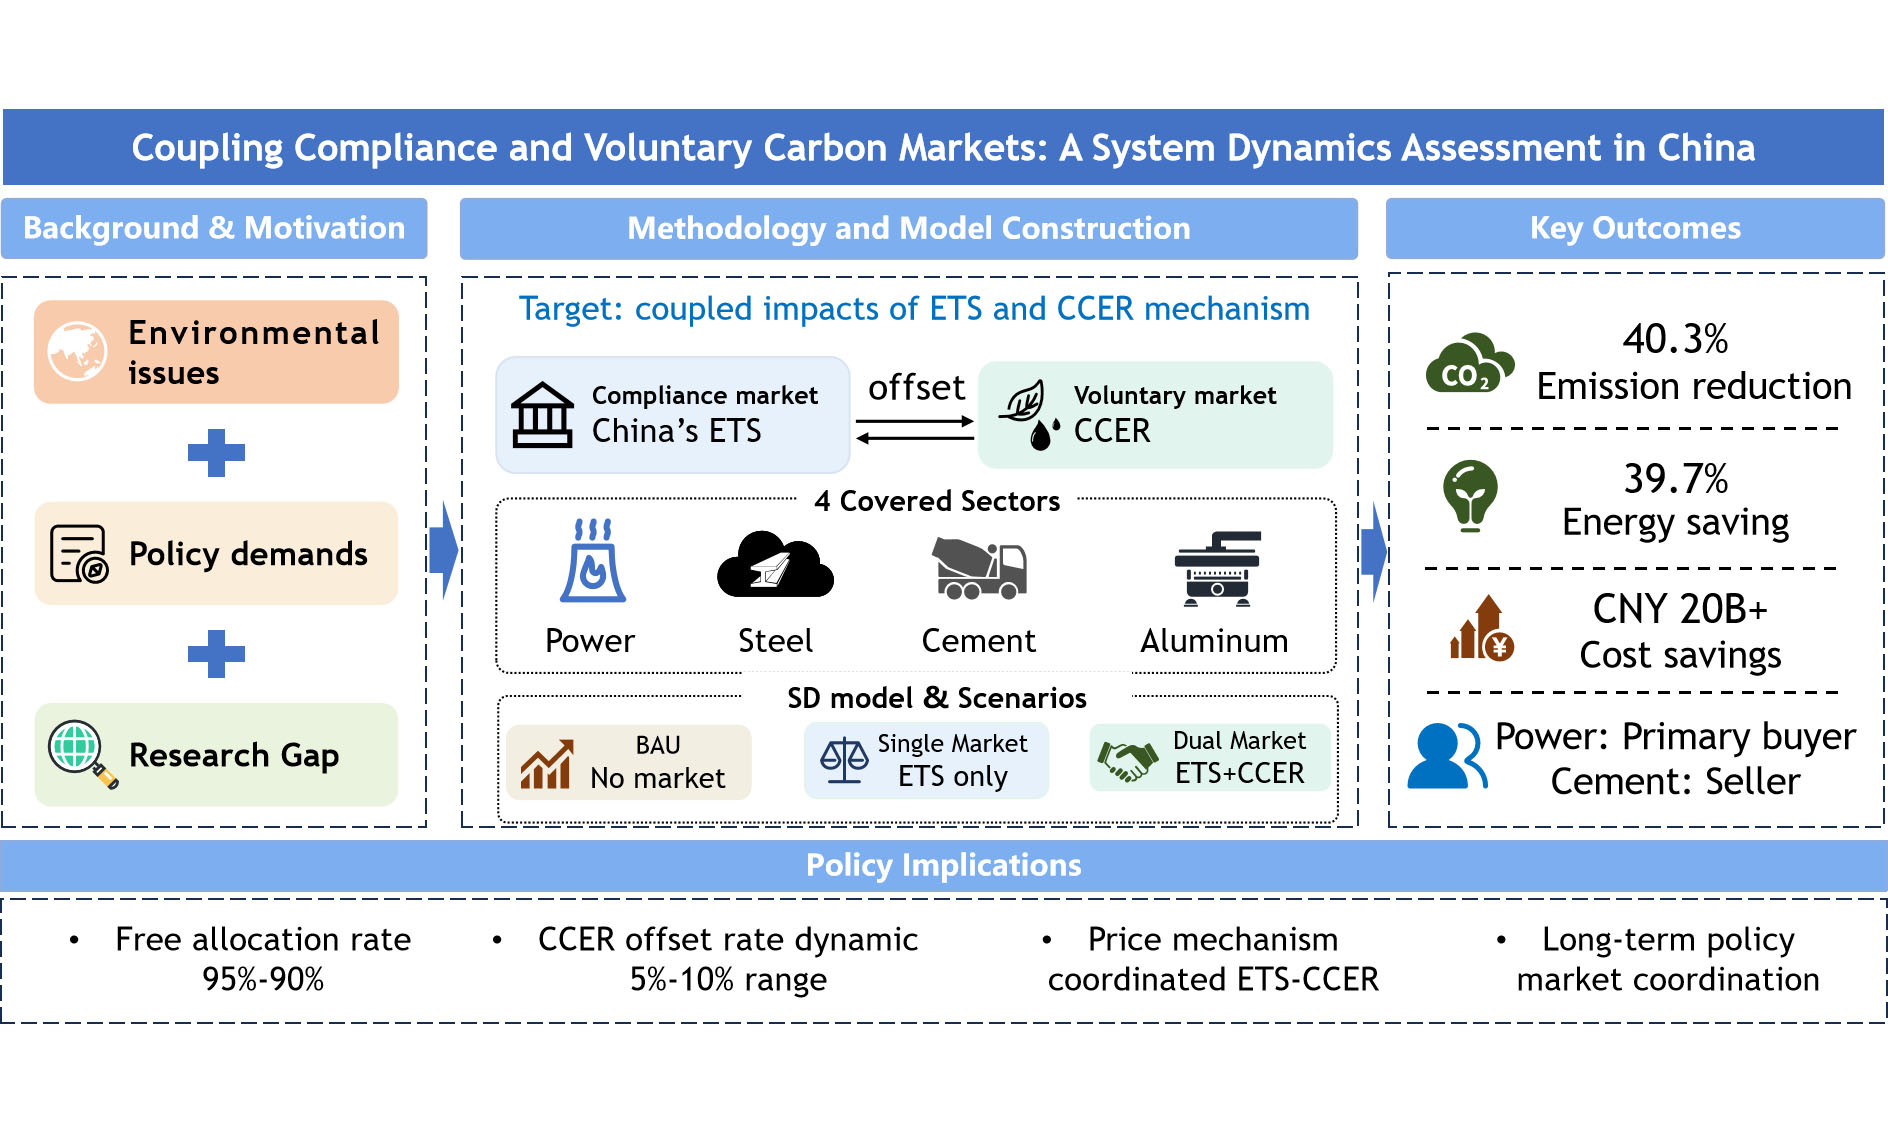
The strategic coupling of compliance and voluntary carbon markets is emerging as a pivotal path for achieving cost-effective decarbonization. However, existing literature seldom captures the dynamic feedback loops, cross-sectoral heterogeneities, and environmental economic benefits inherent in dual-market architectures. To fill this gap, this study develops a sector-specific system dynamics model to evaluate the integrated impacts of coupling China’s Emissions Trading System (ETS) and the China Certified Emission Reduction (CCER) scheme. Three distinct scenarios are modeled: no carbon trading market (BAU), Single Market (ETS-only), and Dual Market (ETS + CCER). Results indicate that the Dual Market scenario achieves emission reductions (40.3%) and energy savings (39.7%) comparable to the Single Market scenario, while the unit abatement cost advantage widens from CNY 0.02 to 0.41 per ton of CO2, and cumulative employment losses are reduced by around 0.19 million. Sectoral analysis reveals the power sector is the predominant buyer in the CCER market, accounting for 59.5% of the total transaction volume, while the cement sector acts primarily as a net seller of carbon allowances in 2030. Sensitivity analyses further confirm the robustness and advantages of coupling markets. Policy implications include gradually reducing the free allocation rate from 95% to 90%, dynamically adjusting the CCER offset rate within 5%-10% under strengthened oversight, and establishing coordinated price mechanisms. These findings provide robust evidence for optimizing dual-market architectures to advance both climate targets and a just, resilient low-carbon transition.
Keywords


 Download PDF
INTRODUCTION
Limiting global warming to 1.5 °C requires achieving net-zero CO2 emissions by around 2050, which involves deep, rapid, and sustainable mitigation efforts[1]. Among climate policy instruments, carbon markets have emerged as an important mechanism, leveraging price signals to drive cost-effective mitigation across jurisdictions[2]. As of February 2026, 41 carbon markets were in operation across over 50 countries and regions, collectively covering about 26% of global anthropogenic carbon emissions[3]. These carbon markets are broadly categorized into two types. One is the compliance market, which is a government-mandated system under which covered entities must surrender allowances equivalent to their verified emissions or face regulatory penalties. The other is the voluntary carbon market, a non-mandatory scheme that enables entities to trade certified emission reductions (CERs), incentivizing additional abatement actions by issuing tradable credits for verified reductions. A critical linkage between these two market types is the use of voluntary market CERs as compliance “offsets”, which means that emission reductions achieved by one entity can be used to compensate for emissions from another entity. This mechanism offers not only regulated companies some flexibility for compliance, but also financial incentives to sectors outside the mandatory coverage, thereby stimulating additional emission reduction and low-carbon innovation[4]. Consequently, many jurisdictions have formally integrated domestic offset programs into their compliance frameworks. For instance, China ETS (with China Certified Emission Reduction), Korea ETS (with Korean Offset Credits), Japan GX-ETS (with the J-Credit Scheme), and California Cap-and-Trade Program (with its domestic offset mechanism) all permit the use of eligible offsets up to quantitative limits.
As the largest developing country and a major carbon emitter, China has pledged to peak CO2 emissions before 2030 and achieve carbon neutrality by 2060. To this end, China has established a comprehensive “1 + N” climate policy framework, within which ETS has emerged as a pivotal market-based instrument[5]. Launched in 2021 and expanded in 2025 to cover the power, steel, cement, and aluminum sectors, China’s ETS now regulates approximately 8 billion tons of CO2 emissions, representing over 60% of national emissions[6]. Concurrently, the China Certified Emission Reduction (CCER) scheme launched in 2024 provides a structured pathway for voluntary offsets. The explicit intention is for these two markets to function in tandem: the ETS drives emission reductions by imposing binding emission caps on regulated entities, while the CCER scheme incentivizes mitigation project developers by creating an additional revenue stream for voluntary emission reduction projects. Yet, whether the coupling of these two markets can deliver cost-effective abatement and how it aligns with decarbonization pathways remain critical concerns for policymakers.
Existing research has examined the effectiveness of the compliance and voluntary carbon markets separately. A nascent but growing body of work investigates the coupling mechanism between these two schemes[7,8]. While offering valuable insights, these studies predominantly adopt a static or equilibrium-based lens, failing to capture the dynamic feedback loops that characterize the interaction between ETS and CCER. Moreover, existing analyses are largely confined to the power sector, overlooking the cross-sectoral interactions and differentiated mitigation burdens introduced by the recent expansion of China’s ETS to include carbon-intensive industries. Furthermore, the coupling mechanism is seldom aligned within the broader climate mitigation strategy perspective.
To address these gaps, this study develops a system dynamics (SD) model that integrates China’s compliance ETS and voluntary CCER markets within a unified, multi-sector framework. Unlike static equilibrium models, the SD approach explicitly captures the time-delayed feedback loops between abatement costs, energy consumption, industrial output, and the endogenous expansion of CCER supply. Therefore, it enables a more nuanced assessment of the long-term, path-dependent implications of dual-market coupling for sustainable development. This study aims to quantify the dynamic environmental, economic, and distributional consequences of coupling China’s ETS and CCER markets across multiple industrial sectors, and to identify critical policy levers for balancing decarbonization depth with socio-economic resilience. By explicitly modeling the interactions between ETS and CCER, this research provides robust evidence for designing dual-market architectures that advance climate mitigation without compromising the broader imperatives of sustainable development. The findings also offer transferable insights for similar jurisdictions seeking to develop integrated carbon markets and promote low-carbon growth.
The main contributions of this study are threefold. First, unlike prior research that treats compliance and voluntary carbon markets in isolation, we construct an integrated framework and systematically analyze the feedback mechanisms linking transaction costs, sectoral output adjustments, and the endogenous evolution of voluntary credit supply. Second, unlike existing studies largely confined to the power sector, we incorporate all four industries currently regulated under China’s expanded ETS (power generation, steel, cement, and aluminum), thereby revealing significant cross-sectoral heterogeneities in trading behavior and mitigation burden-sharing. Third, we embed the analysis within the low-carbon development perspective, offering policy-relevant insights into how specific design parameters can be calibrated to align carbon market operation with the broader goals of a just and resilient low-carbon transition.
The rest of the study is organized as follows. Section “LITERATURE REVIEW” reviews the literature on compliance and voluntary carbon markets. Section “METHODOLOGY” describes the SD model for China’s carbon market, the data sources and scenario settings. Section “RESULTS AND DISCUSSION” reports the simulation results under different scenarios and discusses the results of the sensitivity analysis. Based on the results, the “CONCLUSION” section draws the main conclusions and proposes policy implications and future research directions.
LITERATURE REVIEW
This section provides a comprehensive literature review on the impacts of compliance carbon markets at different research scales, the performance of voluntary carbon markets across different emission-reduction entities, and preliminary research on the coupling mechanism of dual markets.
The impacts of the compliance carbon market
The emission reduction effects and socioeconomic impacts of compliance carbon markets have been widely evaluated from multiple dimensions. Empirical research demonstrates that cap-and-trade systems significantly reduce carbon emissions at the national level, such as China’s ETS and California’s Cap-and-Trade Program[9-11]. Sectoral studies validate the emission reduction effectiveness and further identify the transmission pathways of these effects[12,13]. Beyond direct carbon mitigation, ETS yields broader environmental co-benefits, including reductions in smog and other conventional pollutants[14]. Furthermore, compliance carbon markets generate multifaceted socioeconomic impacts. While the ETS may incur short-term economic costs nationally, these are mitigated in the long run through energy structure improvements and accelerated decarbonization[15]. At the industry level, increased operating costs influence production strategies and pricing decisions toward cleaner methods, particularly in power generation[15,16]. At the micro level, ETS can incentivize green innovation[17] and contribute to enhanced social welfare[18]. Based on these findings, scholars propose policy improvements such as expanding sectoral coverage, optimizing allowance allocation, and designing sector-specific rules[18-20].
The performance of the voluntary carbon market
The voluntary carbon market enhances the engagement of different emission reduction entities and contributes to coordinated mitigation[21,22]. Research indicates that the voluntary carbon market strengthens emission-regulated firms’ flexibility in meeting compliance obligations and can facilitate emission reductions through incentives for innovation and improved practices[23,24]. Participation in the voluntary carbon market can also enhance regulated firms’ cost efficiency[25] and improve their stock market performance[26]. The demand for carbon credits generates economic incentives that drive the development and supply of mitigation projects, thereby supporting sustainable development in host countries and local communities[27], including contributions through renewable energy deployment and poverty alleviation[28,29].
However, there are growing concerns regarding the environmental integrity of the voluntary carbon market. Growing evidence suggests that voluntary carbon projects are of low quality, with excessive issuance of carbon credits and exaggeration of their additionality[30], particularly from reducing emissions from deforestation and forest degradation (REDD+) projects[31]. Additional integrity risks such as carbon leakage and double-counting further undermine credibility[32-34]. To utilize the mitigation contribution and strengthen the complementary role of the voluntary carbon market alongside the compliance market, further improvements are needed in both project development and market-oriented trading mechanisms[35]. Effective market operation and supply-demand balance require strict government oversight and well-designed incentive frameworks [24], including refined and practical methodologies, rigorous project reviews, and clear offset ratios[22,31,36,37].
The impacts of dual-market mechanism coupling
The growing interdependence between compliance and voluntary carbon markets has positioned their coupling as an emerging research frontier in climate policy scholarship. Existing coupling studies primarily focus on the power sector to explore the integration of ETS and CCER. For example, Ye et al.[38] examine the impacts of coupling the ETS with CCER in the power generation industry of Guangdong Province. Zhang and Lin[39] examine how CCER integration reshapes energy consumption patterns in the power sector, while Yang and Mi[8] integrate renewable portfolio standards (RPSs) into a coupled model to analyze electricity-carbon interactions’ effects on electricity prices and market structure. The coupling mechanism is typically formalized by embedding interdependence parameters - such as the emission reductions supply, offset ratios, and price formation rules- into the carbon market scheme. For instance, Zhang and Pang[40] link the ETS and CCER in a dynamic computable general equilibrium (CGE) model through policy parameters governing allowance trading behaviors of regulated entities, including CCER supply volumes, offset ratios, and CCER prices. Similarly, Fan and Chen[7] model voluntary reductions as supplementary allowances and design fiscal stimulus policies to couple the two markets. Simulation results indicate that dual-market frameworks yield multifaceted benefits compared with the single carbon market. Li et al.[22] show that CCER’s lower price can reduce overall abatement costs without compromising emission reduction targets. Paraschiv et al.[41] demonstrate that CCER’s flexibility and cost-effectiveness channel investment toward renewable energy and support structural energy system transformation.
Since dual-market coupling involves dynamic feedback among offset supply, compliance behavior, and abatement costs, its impacts evolve over time and across sectors. Therefore, it is necessary to explicitly capture these interdependencies to evaluate the systematic effects of coupling. While models such as CGE are effective in analyzing long-term economic equilibrium under carbon constraints, they are generally less suited for capturing the operational dynamics, nonlinear feedbacks, and behavioral heterogeneity inherent in real carbon markets[42]. As a methodology designed to analyze complex systems by capturing the causal feedback loops, dynamic interactions, and systematic thinking among system components, system dynamics enables the examination of dynamic change mechanisms through variable adjustments and constraint-based modeling[43,44]. In contrast, SD models explicitly describe how sectoral strategies evolve in response to policies and market signals, and how these interactions drive system-level outcomes over time. Consequently, this methodology has demonstrated broad applicability across diverse domains. Beyond widespread applications in transportation emission pathways[45], energy development[44], and socio-economic and environmental policy-making fields[46,47], SD has increasingly been applied to assess the environmental and economic impacts of market-based carbon mitigation strategies. For example, Zhang et al.[48] explore the low-carbon collaborative strategies in the Beijing-Tianjin-Hebei region under the ETS policy. Chi et al.[49] evaluate the emissions reduction effects of electricity market reforms at the municipal level. Liu et al.[50] apply SD to examine transportation emission pathways and climate commitment credibility within a blockchain-based carbon registry framework. Collectively, these studies affirm the suitability of SD as an analytical tool. By integrating feedback dynamics and multi-dimensional interactions, it provides both theoretical frameworks and empirical support for evaluating carbon market effectiveness and guiding policy design.
In summary, while existing research has substantially advanced our understanding of the environmental efficacy and economic efficiency of carbon markets operating in isolation, critical shortcomings persist regarding their coupled dynamics and policy implications. First, although some studies have examined the coupling effects of ETS and CCER, their interaction mechanism requires more sophisticated design. Second, previous research has predominantly focused on the power sector alone, overlooking the cross-sectoral interactions under the expanding ETS coverage and recently relaunched CCER. Third, existing studies lack holistic, macro-level impact assessments that align with the real-world climate policy architecture. To address these gaps, this study investigates the impacts of integrating the ETS and CCER through a more in-depth analysis. First, we develop an SD model comprising four subsystems, which cover the power generation, steel, cement, and aluminum sectors and capture dynamic feedback mechanisms as well as heterogeneity in industrial emission reductions. Second, we design three scenarios to evaluate the environmental and economic impacts of the dual-market framework. Third, we identify key policy parameters through sensitivity analyses and assess their differential effects on emission reductions and economic costs. In doing so, this study provides a robust, policy-relevant evidence base for optimizing dual-market architectures in China and beyond.
METHODOLOGY
Model boundary and basic assumptions
This study develops a sector-level SD model to assess the coupling effects of China’s ETS and CCER within a multi-sector carbon market framework. Figure 1 illustrates the research framework. It consists of four interrelated subsystems, i.e., the economic, energy, environmental, and low-carbon policy subsystems, which are dynamically interconnected through complex feedback loops and associated variables. First, sectoral output targets determined by the economic subsystem drive fossil fuel consumption in the energy subsystem according to sector-specific energy intensities. Second, energy consumption directly generates CO2 emissions, which flow to the environmental subsystem. Third, the environmental subsystem evaluates actual emissions against the emission cap and the carbon intensity target, triggering the activation of the low-carbon policy subsystem. Fourth, the low-carbon policy subsystem operates two complementary carbon market mechanisms: the ETS and CCER. Regulated entities comply with emission constraints by acquiring carbon emission allowance (CEA) or CCER to meet compliance obligations. The transaction costs incurred from market participation feed back into the economic and energy subsystems, exerting downward pressure on subsequent sectoral output and energy consumption. Finally, revenues generated from CCER transactions provide a direct economic incentive that stimulates investment in renewable energy projects, thereby expanding the future CCER supply and influencing the future energy supply structure. This closed-loop structure captures the synergistic interactions between economic activity, energy use, environmental impact, and market-based policy instruments. This study considers the transmission path of the impact of transaction costs on industry output through energy consumption, without involving elasticity, cost transfer, or revenue recycling.
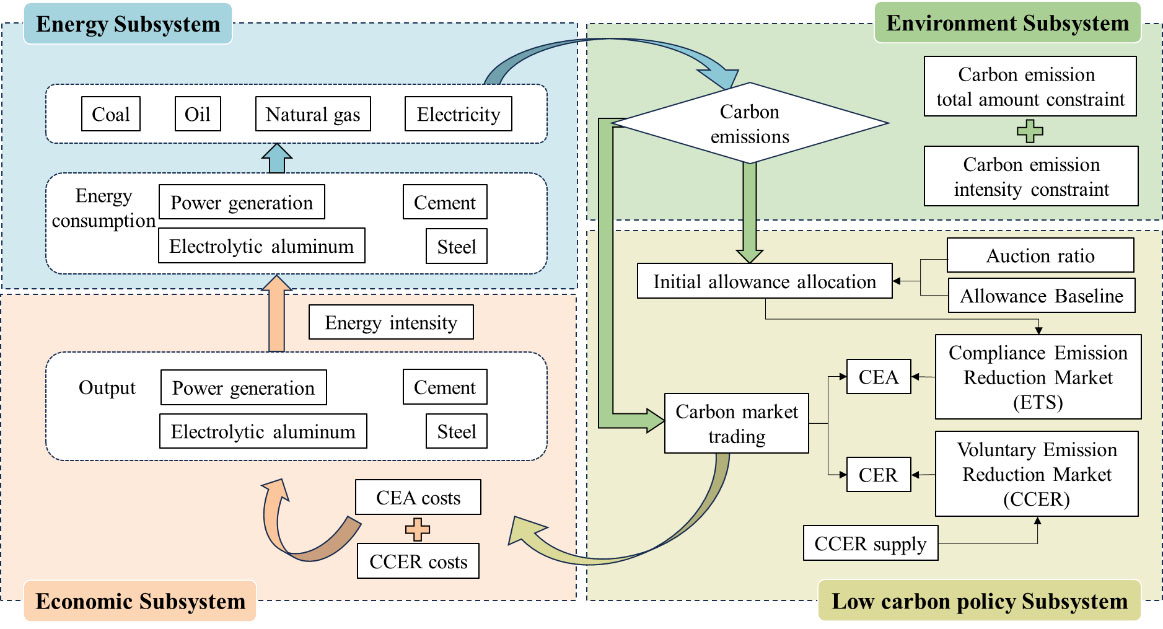
Figure 1. Model framework diagram. The economic, energy, environmental, and low-carbon policy subsystems are interconnected through sectoral output, energy consumption, carbon emissions, and carbon trading costs. CEA: Carbon emission allowance; CCER: China Certified Emission Reduction; CER: certified emission reduction; ETS: China’s Emissions Trading System.
The SD model developed in this study is designed to simulate the dynamic processes, inter-sector interactions, and policy-induced behavior responses within China’s national dual-carbon market scheme, rather than to predict a long-term general equilibrium. To simplify the representation of the real-world carbon market and concentrate on the core research objectives, this study defines the following model boundaries and assumptions to highlight the coupling mechanism between the ETS and CCER scheme, as summarized in Table 1.
Assumptions in this study
| System | Assumption |
| General model boundaries and key assumptions | • The model covers four sectors (power generation, steel, cement, and aluminum), which are included in the expanding national ETS. All other industries are aggregated into a simplified “other industries” category • To isolate the causal effects attributable specifically to the dual-carbon market architecture, the model focuses exclusively on interactions between the ETS and CCER mechanisms. All other policy instruments (such as renewable energy subsidies or carbon taxes) are explicitly excluded from the scope of analysis • Policy trends and targets used in the simulation process refer to national planning documents such as China’s 14th Five-Year Plan and its updated Nationally Determined Contributions (NDC), along with relevant industrial databases • The model incorporates separate price formation mechanisms for ETS allowances and CCER credits based on expert assessments and historical carbon market observations. Price inversion between CCER and allowances is considered abnormal and not included in the analysis |
| The macroeconomic subsystem | • GDP is estimated using a bottom-up approach that aggregates the output values of industries. The growth rate of industrial output is exogenously determined, while its level is subject to dynamic adjustments in response to feedback from the overall transaction costs • All monetary values (e.g., GDP, output, costs, revenues) are expressed in constant 2005 CNY using an appropriate GDP deflator to ensure temporal comparability • The model explicitly accounts for direct compliance expenditures arising from market transactions. Indirect costs (e.g., costs related to administration, energy transition, and competitiveness) are not considered |
| The energy subsystem | • This model accounts for fossil energy consumption in industrial production and self-generation, with fuel use for self-generation estimated from self-generated electricity • Energy types are classified as coal, oil, natural gas, and self-owned electricity, and their consumption is calculated based on energy consumption intensity and the output of each industry |
| The environmental subsystem | • Consistent with the energy subsystem, only direct CO2 emissions from fossil fuel combustion are calculated. Indirect emissions associated with purchased electricity are excluded • The annual carbon intensity target is calculated based on the exogenous benchmark carbon intensity and the carbon intensity reduction rate of the NDC target • The total carbon emission cap for each year is derived from the annual carbon intensity target and the projected GDP for that year |
| The low-carbon policy | • To examine the potential effects of market coupling, this study adopts a counterfactual setting in which CCER is introduced concurrently with the ETS in 2021, with the first compliance cycle covering 2020 emissions • In the ETS, enterprises obtain initial allowances via a combination of free allocation and auctions •Carbon allowances purchased are restricted to use by enterprises within the current compliance cycle. Unused CCERs can be banked for use in future compliance periods • Based on actual market trading conditions, firms first obtain emission allowances and conduct auctions in the primary market, followed by trading activities in the secondary market. Firms prioritize using CCER credits for compliance due to their relatively lower cost, followed by CEAs. If a shortfall remains, the government releases additional allowances through the allowance reserve and market-based adjustment mechanism at the prevailing market price. Given the goal of carbon peak by 2030, this model has no emissions cap limit • The incremental supply of CCER is primarily driven by investment in offshore wind power projects, with its growth rate positively influenced by the revenue generated from CCER transactions, forming a reinforcing feedback loop |
Causal-loop diagram
Before conducting the SD modeling, it is essential to present the causal relationships among key variables and parameters hierarchically[44]. Based on the model framework diagram and defined system boundaries, this study constructs a causal loop diagram to elucidate the interdependencies and mutual influences among system variables, as illustrated in Figure 2. The descriptions of the key variables are summarized in Table 2, and more detailed variable explanations of the model are presented in Supplementary Table 1.
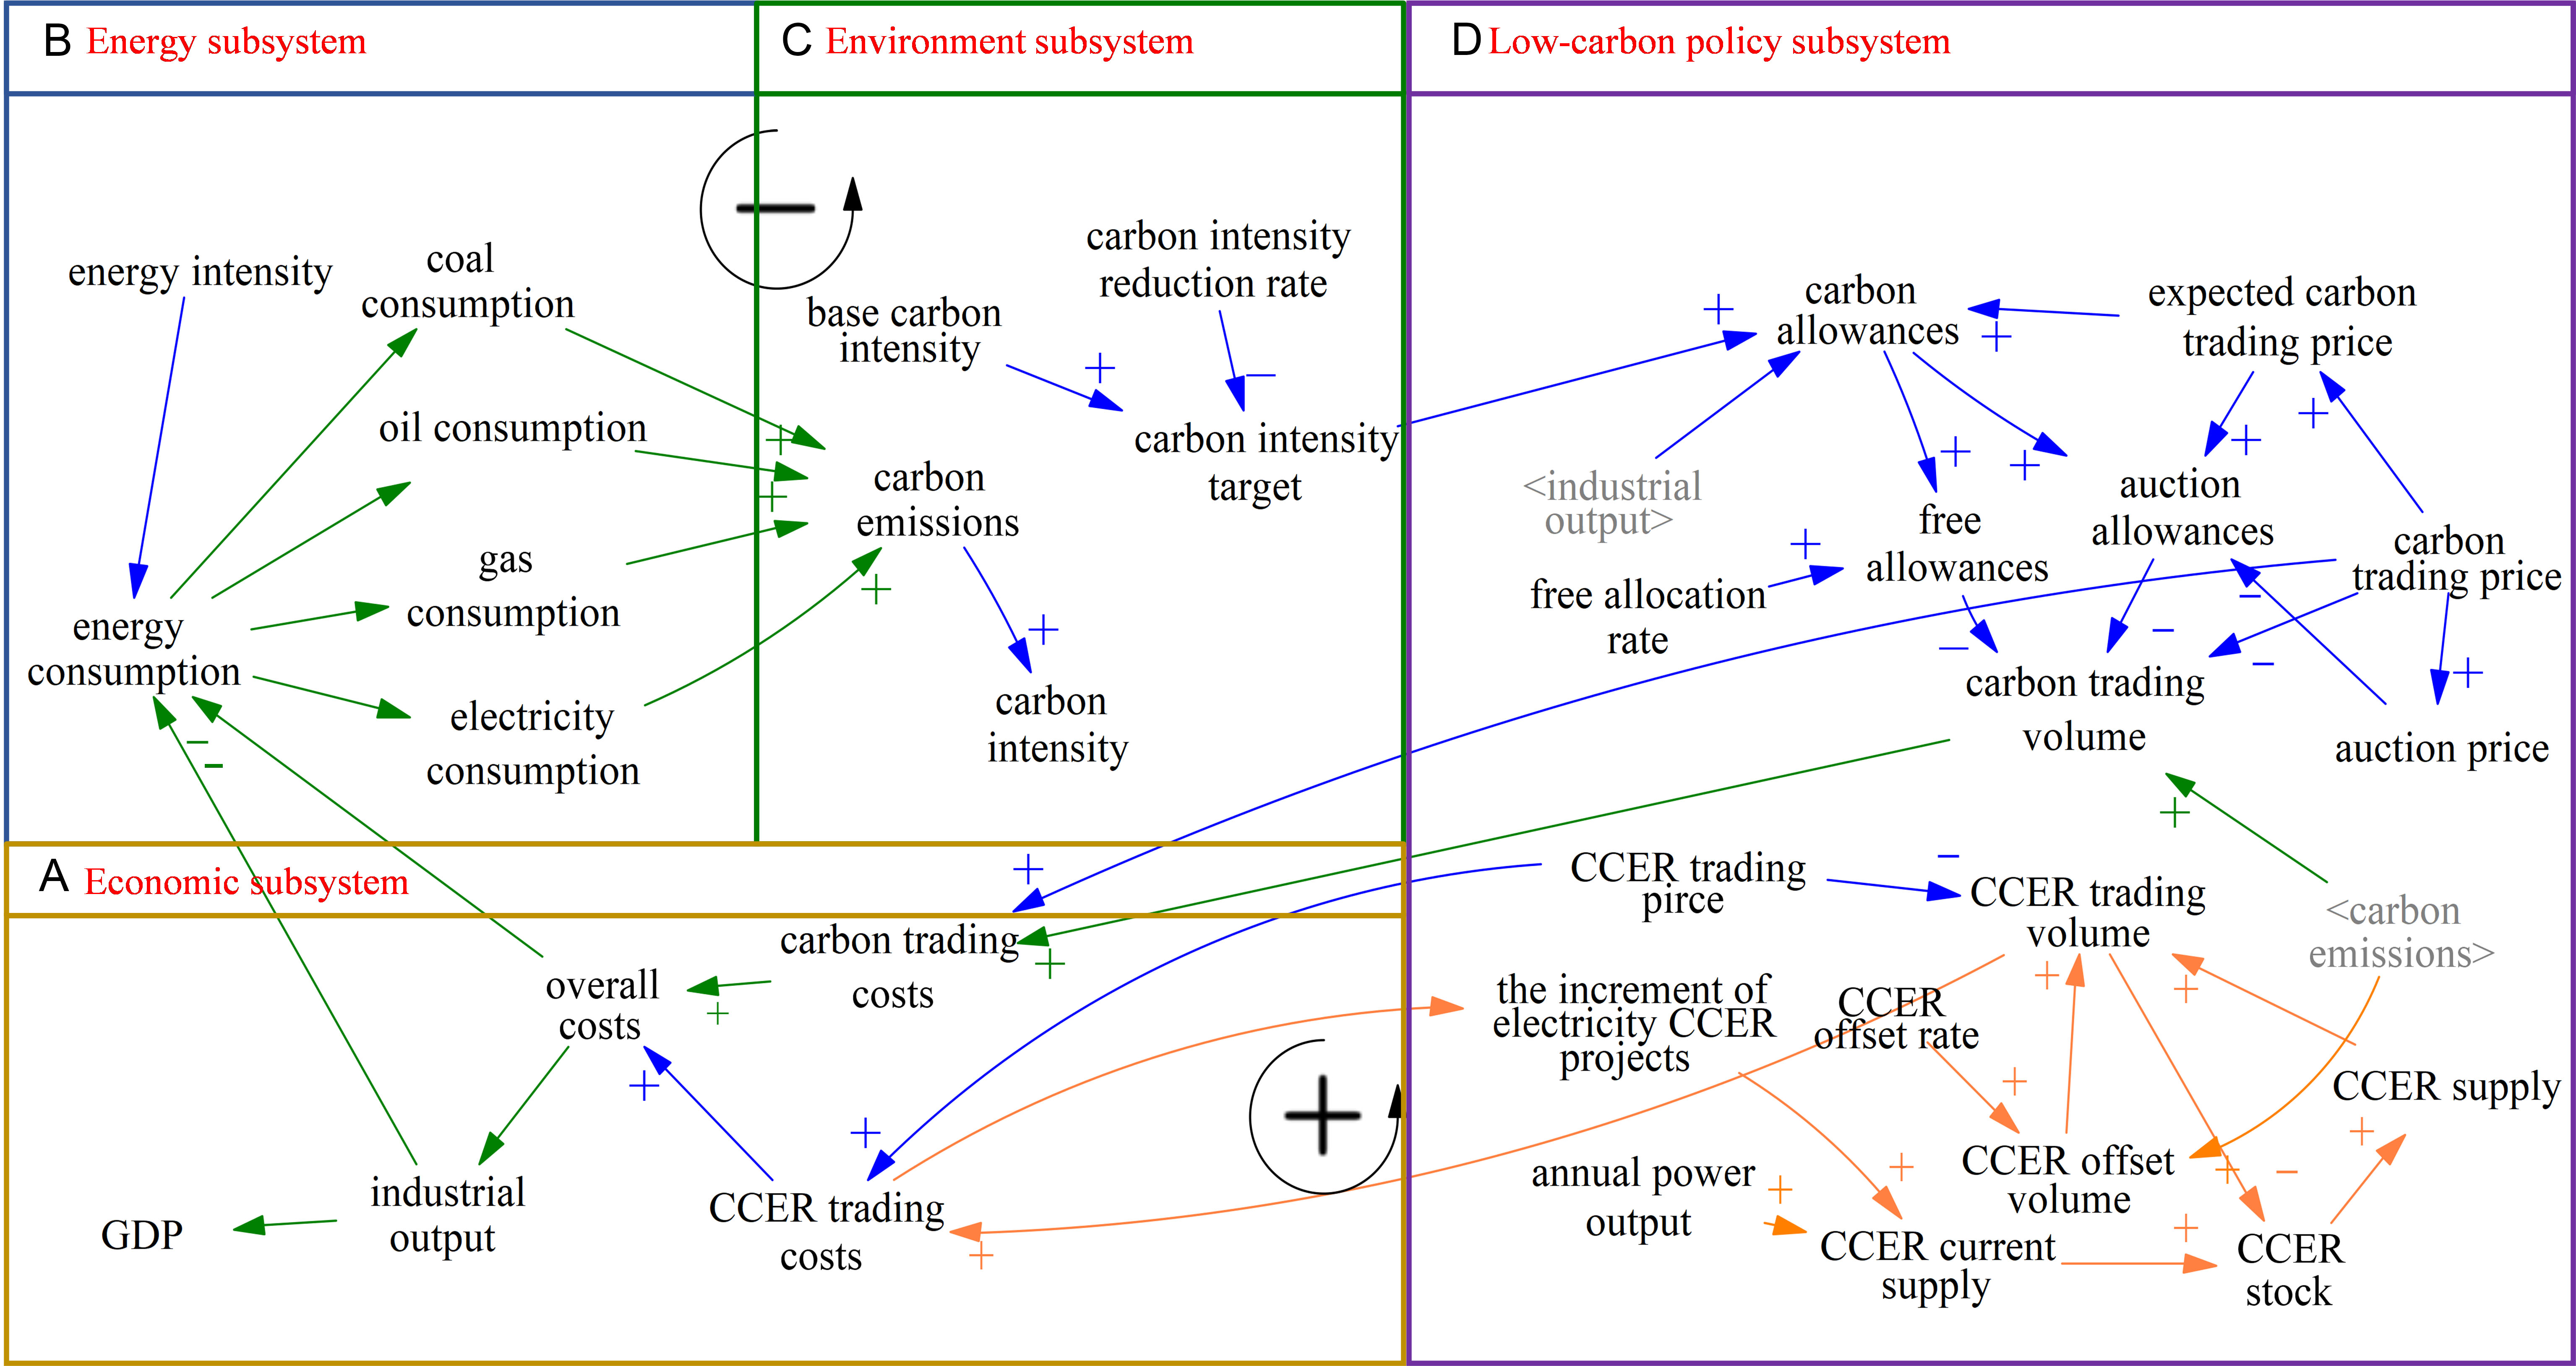
Figure 2. Causal loop diagram. (A) shows the economic subsystems involved in the causal loop; (B) shows the energy subsystems involved in the causal loop; (C) shows the environment subsystems involved in the causal loop; (D) shows the low-carbon policy subsystems involved in the causal loop. “+” and “-” indicate positive and negative causal relationships, respectively. CCER: China Certified Emission Reduction.
Description of the variables in the causal loop diagram
| Subsystem | Variable | Predicting variables |
| Macroeconomic subsystem | Industrial output | Exogenous |
| Industrial employment | Industrial output, industrial labor productivity | |
| GDP | The sum of industrial outputs | |
| Carbon trading costs | Carbon trading volume, carbon trading price | |
| CCER trading costs | CCER trading volume, CCER price | |
| Overall costs | Carbon trading costs, CCER trading costs | |
| Energy subsystem | Energy consumption | Energy intensity, overall costs, industrial output |
| Energy intensity | Exogenous | |
| Coal consumption | Coal proportion of sectoral total energy consumption | |
| Oil consumption | Oil proportion of sectoral total energy consumption | |
| Gas consumption | Gas proportion of sectoral total energy consumption | |
| Electricity consumption | Electricity proportion of sectoral total energy consumption | |
| Environmental subsystem | Carbon emissions | Energy consumption by fuel type and corresponding emission factors |
| Carbon intensity | Total carbon emissions and GDP | |
| Base carbon intensity | Exogenous | |
| Carbon intensity target | Base carbon intensity, carbon intensity reduction rate | |
| Carbon intensity reduction rate | Exogenous (policy pathway from national plans such as the 14th Five-Year Plan and updated NDC targets) | |
| Low-carbon policy subsystem (ETS) | Carbon allowances | Carbon intensity target, industrial output |
| Free allocation rate | Scenario parameter, exogenous | |
| Free allowances | Free allocation rate, carbon allowances | |
| Auction allowances | Carbon allowances, free allowances | |
| Expected carbon trading price | Exogenous | |
| Auction price | Carbon trading price | |
| Carbon trading price | Scenario parameter, exogenous, market trading data | |
| Carbon trading volume | Carbon emissions, free allowances, auction allowances, CCER offset volume | |
| Low-carbon policy subsystem (CCER) | CCER trading price | Scenario parameter, exogenous, market trading data |
| CCER supply | CCER stock | |
| CCER trading volume | CCER offset volume, CCER supply | |
| CCER offset rate | Scenario parameter, exogenous | |
| CCER offset volume | CCER offset rate, carbon emissions | |
| CCER current supply | Annual power output, the increment of electricity CCER projects | |
| Annual power output | Exogenous | |
| The increment of electricity CCER projects | Annual renewable power output, CCER trading costs | |
| CCER stock | CCER current supply, banked CCER carried over |
This causal-loop diagram captures a negative feedback loop (marked with green) and a positive feedback loop (marked with orange):
(1) Negative feedback loop: industry output added → (+) energy consumption → (+) CO2 emissions → (+) transaction costs → (-) industry output added
Energy inputs serve as critical drivers of economic growth. As industrial output increases, energy consumption rises proportionally, directly increasing CO2 emissions. To avoid non-compliance penalties, regulated entities must purchase additional allowances or CCERs to meet compliance obligations, incurring higher transaction costs. These increased costs reduce industrial profitability and subsequently suppress economic output and future energy inputs, creating a dual dampening effect.
(2) Positive feedback loop: annual CCER increment (+) CCER supply → (+) offset volume → (+) CCER transaction revenue → (+) annual CCER increment.
Recently, offshore wind power projects have accounted for more than half of China’s voluntary carbon market projects, serving as the dominant source of CCER. Driven by supportive renewable energy policies, the development of offshore wind projects has accelerated markedly. This rapid expansion has substantially increased the current CCER increment, which - combined with the CCER stock - forms the total CCER supply available for compliance use. In pursuit of cost-effective compliance solutions, regulated entities increasingly purchase CCERs, generating transaction revenue that directly incentivizes further project development - particularly in the offshore wind sector - thereby reinforcing a self-sustaining supply feedback loop.
Stock and flow diagram
For quantitative analysis, a stock-and-flow diagram is developed based on the causal-loop diagram to simulate and understand the dynamic interactions and changes among variables over time. The model identifies stock variables and flow variables of each subsystem. A brief description of each subsystem is summarized below, while the full specifications of variables and equations are presented in Supplementary Model Equations.
Macroeconomic subsystem
The macroeconomic subsystem serves as the core component of this model, integrating industry-specific activities with macroeconomic output and socioeconomic resilience [Figure 3]. A full-page version of the stock-and-flow diagram is provided in Supplementary Figure 1. Sectoral economic output is calculated through flow equations and discrete time steps, and changes in output levels are directly affected by the costs associated with the carbon market, highlighting a crucial feedback mechanism from policy interventions to economic behavior.
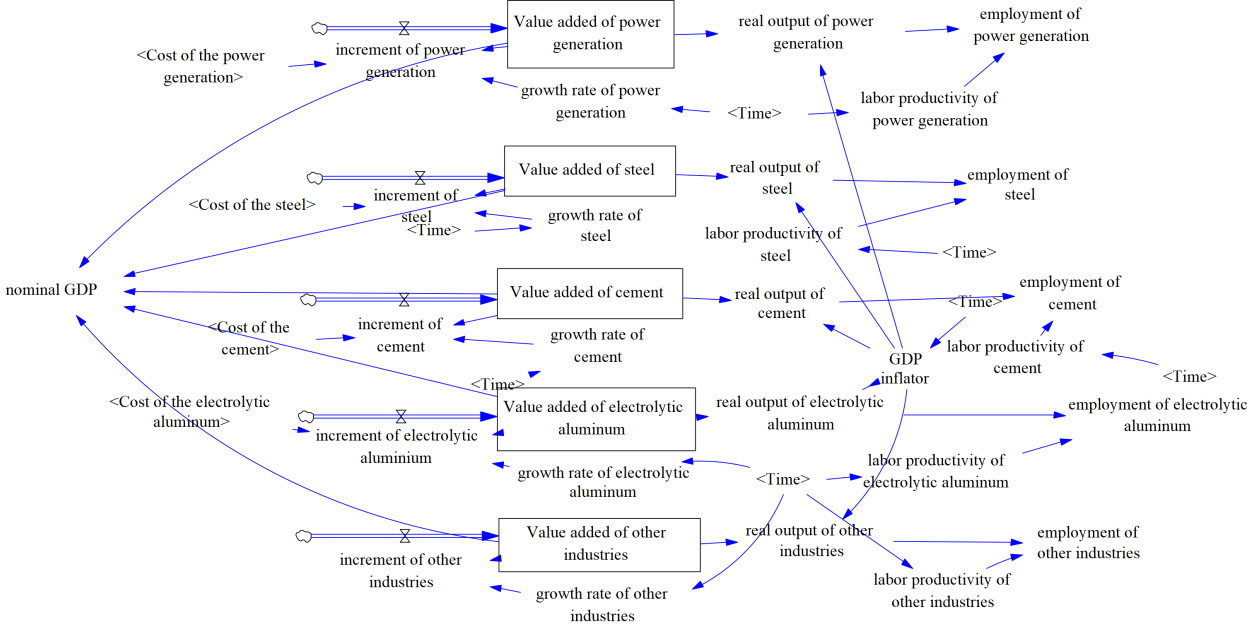
Figure 3. Stock flow diagram of the macroeconomic subsystem.
Where t, ∆Yi, Yi, gi,
Where LPi, Ni, gLPi represent the labor productivity of industry i, employment of industry i, compound annual growth rate of labor productivity.
To assess the intersectoral interactions in the carbon market, this study focuses on four carbon-intensive and energy-intensive industries, namely power generation, steel, cement, and electrolytic aluminum sectors. Due to limitations in the availability of sector-specific data, these sectors are reclassified following the methodology employed by Yuan et al.[51] and Shan et al.[52]. The classification is based on the Industrial Classification for National Economic Activities (GB/T 4754-2017), and the resulting categorization of industries is presented in Table 3.
Sector classification
| Sector | Sub-sectors |
| Power generation | Production and distribution of electric power and heat power, production and distribution of gas, production and distribution of tap water |
| Steel | Smelting and pressing of ferrous metals, manufacture of metal products |
| Cement | Manufacturing of non-metallic mineral products |
| Aluminum | Smelting and processing of non-ferrous metals |
Energy subsystem
Building on the output targets derived from the economic subsystem, the energy subsystem [Figure 4] models the energy consumption patterns across various industries. A full-page version of the stock-and-flow diagram is provided in Supplementary Figure 2. Each industry utilizes a combination of coal, oil, and natural gas, along with electricity from self-generation in certain sectors. Transaction costs incurred for regulatory compliance influence firms’ energy-use decisions and exert a negative influence on energy consumption[38]. To capture this feedback mechanism, the model introduces an energy adjustment coefficient (φi), defined as the change in energy consumption per unit of transaction cost. Drawing on the simulated effects of carbon trading on the consumption of different energy types reported by Lin and Jia[53], sector-specific coefficients are constructed by weighting these responses according to each sector’s energy mix. This coefficient enables the model to capture the differential suppression effects across fuel types.
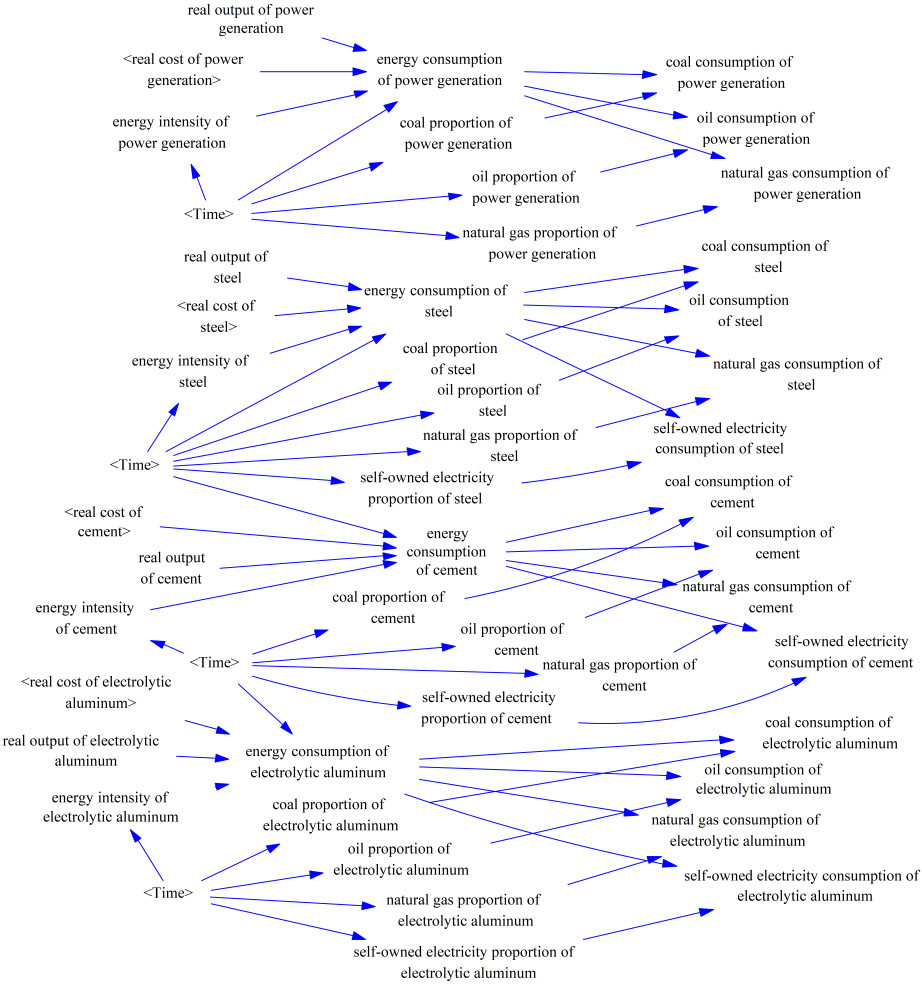
Figure 4. Stock flow diagram of the energy subsystem. <Time> denotes simulated time, and <real cost > variables represent inflation-adjusted costs expressed in constant 2005 CNY.
Where Ei, EIi represent the energy consumption, energy intensity, and φi is the energy adjustment coefficient.
Environmental subsystem
The environmental subsystem [Figure 5] models CO2 emissions arising from energy consumption and imposed carbon constraints. A full-page version of the stock-and-flow diagram is provided in Supplementary Figure 3. Carbon emissions are estimated based on emission factors and energy consumption.
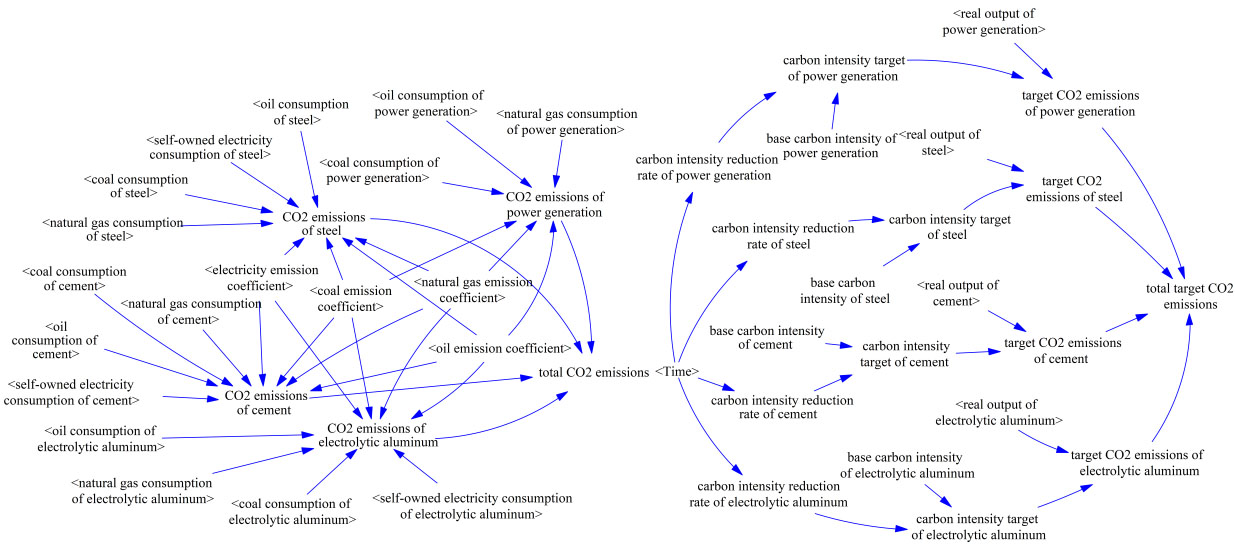
Figure 5. Stock flow diagram of the environmental subsystem.
The environmental carbon capacity function serves as a dynamic emissions cap, derived from the emissions intensity targets, which can also be expressed as the carbon emissions target. When actual emissions exceed this cap, firms are required to purchase additional allowances or carbon credits to address the compliance gap.
As the carbon intensity target decreases due to technological advancements and structural changes, the allowable carbon budget diminishes, thereby supporting long-term emissions reduction objectives.
Where CEi denotes the CO2 emissions, EFf is the emission factor for energy type f,
Low-carbon policy subsystems
The low-carbon policy subsystem incorporates two core trading modules: allowance trading within the compliance carbon market [Figure 6] and emission reduction trading within the voluntary carbon market [Figure 7]. Full-page versions of stock-and-flow diagrams are provided in Supplementary Figures 4 and 5. The two markets are coupled in a two-way manner: (1) the ETS compliance gap creates endogenous demand for CCER under the offset rule, and (2) CCER trading revenues feed back to future CCER supply and emission reduction behaviors via project certification and issuance dynamics and thus alter allowance demand, the secondary carbon market trading volume, and costs. In practice, regulated entities first obtain allowances via free allocation and auctioning in the primary market, and then trade in the secondary market based on their emission gaps or surpluses.
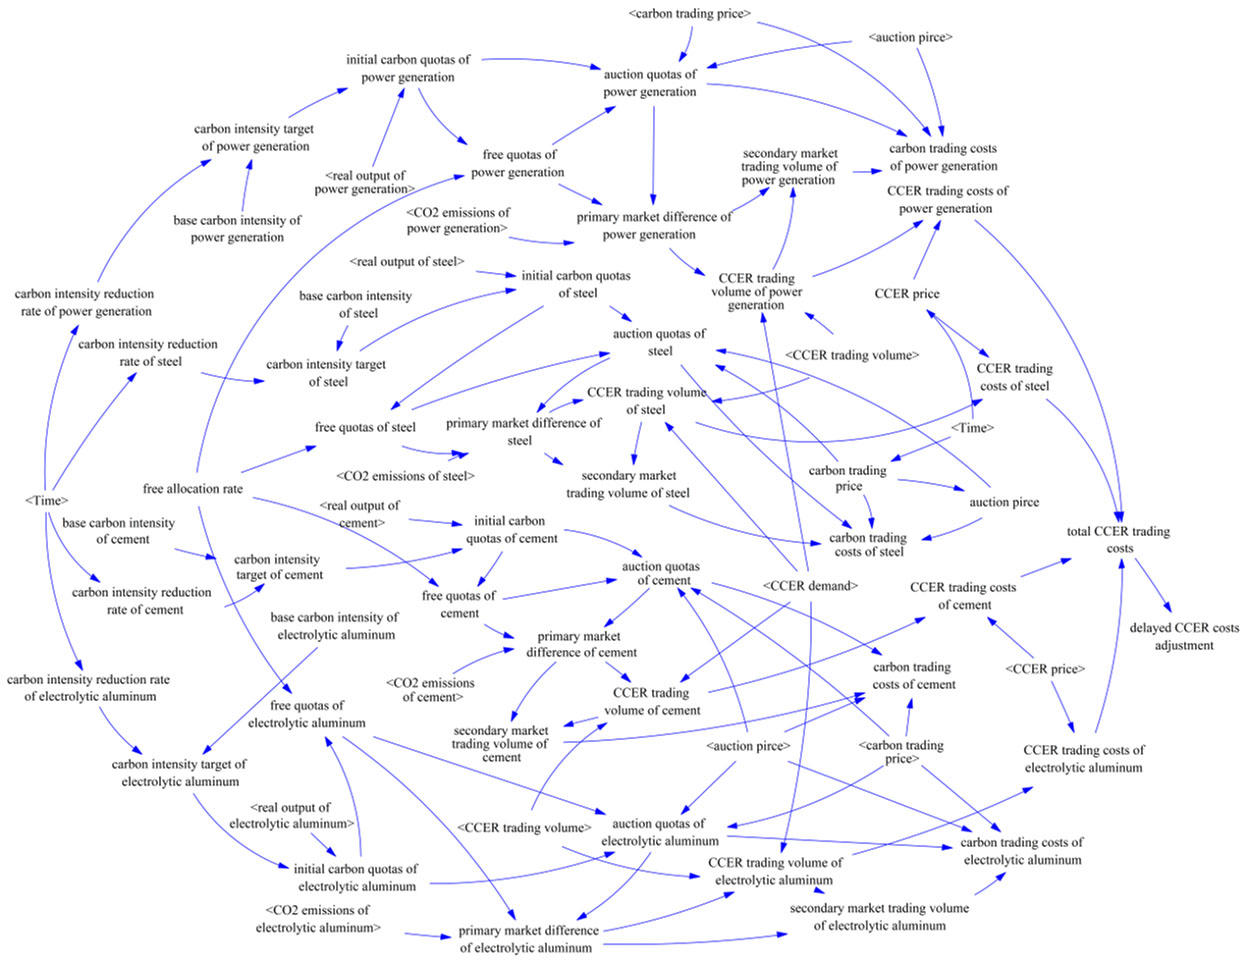
Figure 6. Stock flow diagram of the allowance trading module. CCER: China Certified Emission Reduction.
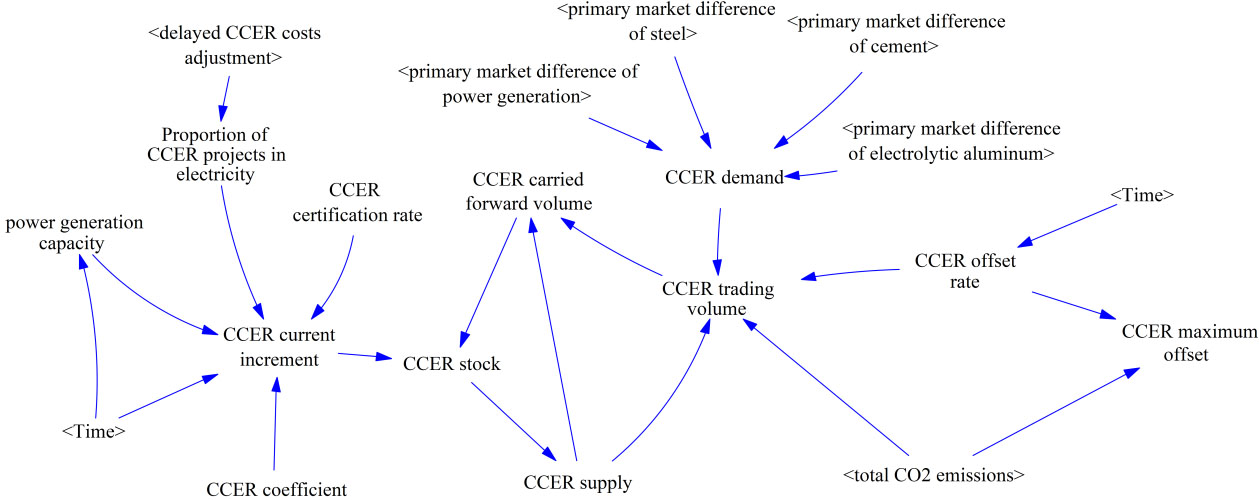
Figure 7. Stock flow diagram of the emission reductions trading module. CCER: China Certified Emission Reduction.
(1) Trading in the primary carbon market.
In ETS, initial allowances are allocated through a combination of free distribution and auctioning at the beginning of each compliance period.
Due to variations in energy consumption patterns and abatement capacities across sectors, certain industries emerge as net sellers while others act as buyers in ETS. If a firm’s actual emissions exceed its initial allowances, it is required to purchase either additional allowances or carbon credits to meet its compliance obligations.
Where Ai,
(2) Trading in the secondary carbon market.
(a) Trading in the CCER market.
The coupling is operationalized through an offset constraint that caps how much CCER can be used to cover emissions in each sector.
Given the relative cost advantage of CCER, firms tend to prioritize their use up to the stipulated offset limit. Excess allowances held by low-emission entities can be traded in the secondary carbon market. The transaction volume is determined jointly by the emission gap and the maximum permissible CCER offset amount, which means a larger ETS gap or a higher offset ratio directly increases CCER retirement.
Where
(b) Trading in the ETS market.
After CCER use is accounted for, the residual compliance gap is settled through secondary carbon market allowance trading. Equation 17 captures the interaction between CCER and ETS that higher CCER use reduces secondary allowance demand, thereby easing pressure on the allowance market.
Where
Where pauc, pccer and pquota represent the price of the auction quota, CCER, and the quota in the secondary ETS market, respectively. The auction costs of the primary market and the trading costs of the secondary market jointly constitute the transaction costs of the ETS.
CCER operates as a complementary mechanism to ETS, offering more flexible and cost-effective pathways for emissions compliance. The untraded offset CCER for the current period can be carried forward to the CCER stock and traded in subsequent years, as shown in Equations 19 and 20. Historical CCER issuance data and recent official project approvals show that renewable energy projects, particularly offshore wind, account for more than 50% of CCER projects and issuances. Furthermore, due to standardized methodologies, offshore wind projects enable precise and verifiable emissions reductions. Consequently, the model assumes that most carbon credits are generated from offshore wind project.
Revenues derived from emission reduction transactions enhance the proportion of such projects through the CCER cost adjustment coefficient
Where Sccer, CCERstock, PGC(t) and
Data source and scenario settings
Data source
To ensure the robustness and credibility of the simulation results, this study draws upon data from official national statistical sources, government policy documents, industry reports, and relevant literature. Historical socioeconomic and energy variables are primarily obtained from official statistical yearbooks, while policy-related and market parameters are determined based on observed market information, existing policy rules, literature evidence, expert judgment, and model calibration where direct observations are unavailable. The specific data sources are outlined as follows: (1) Economic data are obtained from the China Statistical Yearbook and adjusted to the constant price of 2005 using a GDP deflator; (2) Energy data are obtained from the energy balance and terminal energy consumption sheets in the China Energy Statistics Yearbook, as well as relevant industry policy reports; (3) Emission factors follow China’s official CO2 accounting methodology, and the electricity-related factor is based on the national power grid baseline emission factor, which also links offshore wind power generation to emission reductions supply; (4) Carbon market parameters, including allowance price, CCER price, free allocation ratio, offset rate, and certification rate, are collected from China Carbon Market Information Network, policy documents, pilot ETS programs, and relevant studies. Detailed justifications for the key assumptions and parameter settings are provided in Supplementary Table 1. The simulation period spans from 2005 to 2030 with an annual time step.
Scenario settings
This study defines three distinct scenarios: the baseline scenario with no carbon trading market (BAU), the single-market scenario (SM) with the compliance carbon market, and the dual-market scenario (DM) integrating the voluntary carbon market with the compliance carbon market. Detailed descriptions of these scenarios are provided in Table 4.
Scenario descriptions
| Scenario | ETS | CCER | Free allocation ratio | Allowance price | CCER price | Offset rate | Certification rate |
| BAU | × | × | / | / | / | / | / |
| SM | √ | × | 95% | 100 | / | / | / |
| DM | √ | √ | 95% | 100 | 80 | 5% | 30% |
To ensure alignment with real-world conditions, the model was validated through structure verification test, dimensional consistency test, extreme condition test, and stability test[54,55].
(1) Structure verification test. The model structure, variable definitions, stock-flow relationships, feedback loops, and policy constraints were systematically examined. Key causal links among carbon prices, allowance allocation, CCER offsets, energy consumption, compliance costs, and emissions were traced to ensure consistency with the operational logic of China’s carbon market. The results showed no evident structural inconsistencies, indicating that the model can reasonably represent the main feedback mechanisms of the coupled carbon market system.
(2) Dimensional consistency test. All model equations were checked using Vensim’s built-in unit-checking function. Units related to emissions, energy consumption, carbon prices, transaction costs, and time were verified across all equations. All equations passed the dimensional consistency test, confirming the model is internally consistent in units.
(3) Extreme condition test. Key policy parameters were varied to their theoretical extremes to assess whether the model generated plausible behavior under stressed conditions. When the CCER offset rate was varied from 0 to 1, CCER trading volume and emission-reduction outcomes changed within the constraints imposed by market supply and compliance demand, without producing unrealistic behavior. The free allocation ratio was also adjusted over a wide range. A lower free allocation ratio increased firms’ exposure to allowance purchasing costs and strengthened the carbon-cost signal, thereby altering the trade-off among allowance purchases, internal abatement, and CCER use. The resulting changes remained consistent with the expected operating logic of the market.
(4) Stability test. The model was simulated using different time steps (dt = 1, 0.5, and 0.25 years). Although minor differences were observed in annual values, the overall trends, turning points, and long-term trajectories of major variables remained highly consistent across all time-step settings. This indicates that the model behavior is not sensitive to computational time granularity and demonstrates satisfactory numerical stability for subsequent scenario and policy analysis.
RESULTS AND DISCUSSION
Comparisons of carbon emissions and energy consumption
Figure 8 illustrates total carbon emissions under the three scenarios. In the BAU scenario, carbon emissions rise steadily from 3,358.34 million ton (Mt) in 2005 to a peak of 7,990.16 Mt in 2023, then decline to 7378.69 Mt by 2030. In contrast, carbon emissions under the Single Market scenario show an overall downward trend from 2020, reaching 4,381.46 Mt by 2030, 40.6% lower than under the BAU scenario. The Dual Market scenario also exhibits a downward trend, with total emissions decreasing to 4,408.53 Mt by 2030, showing a 0.62% higher emission compared to the Single Market scenario. The reason is that the introduction of CCER enables regulated entities to meet their compliance obligations through purchasing additional emission reductions, thereby weakening incentives for their own abatement efforts[41]. This conclusion aligns with previous research on the mitigation effects of CCER[40], highlighting the necessity of adjusting policy stringency in the design of the dual market system to prevent overreliance on CCER and ensure effective emission reductions.
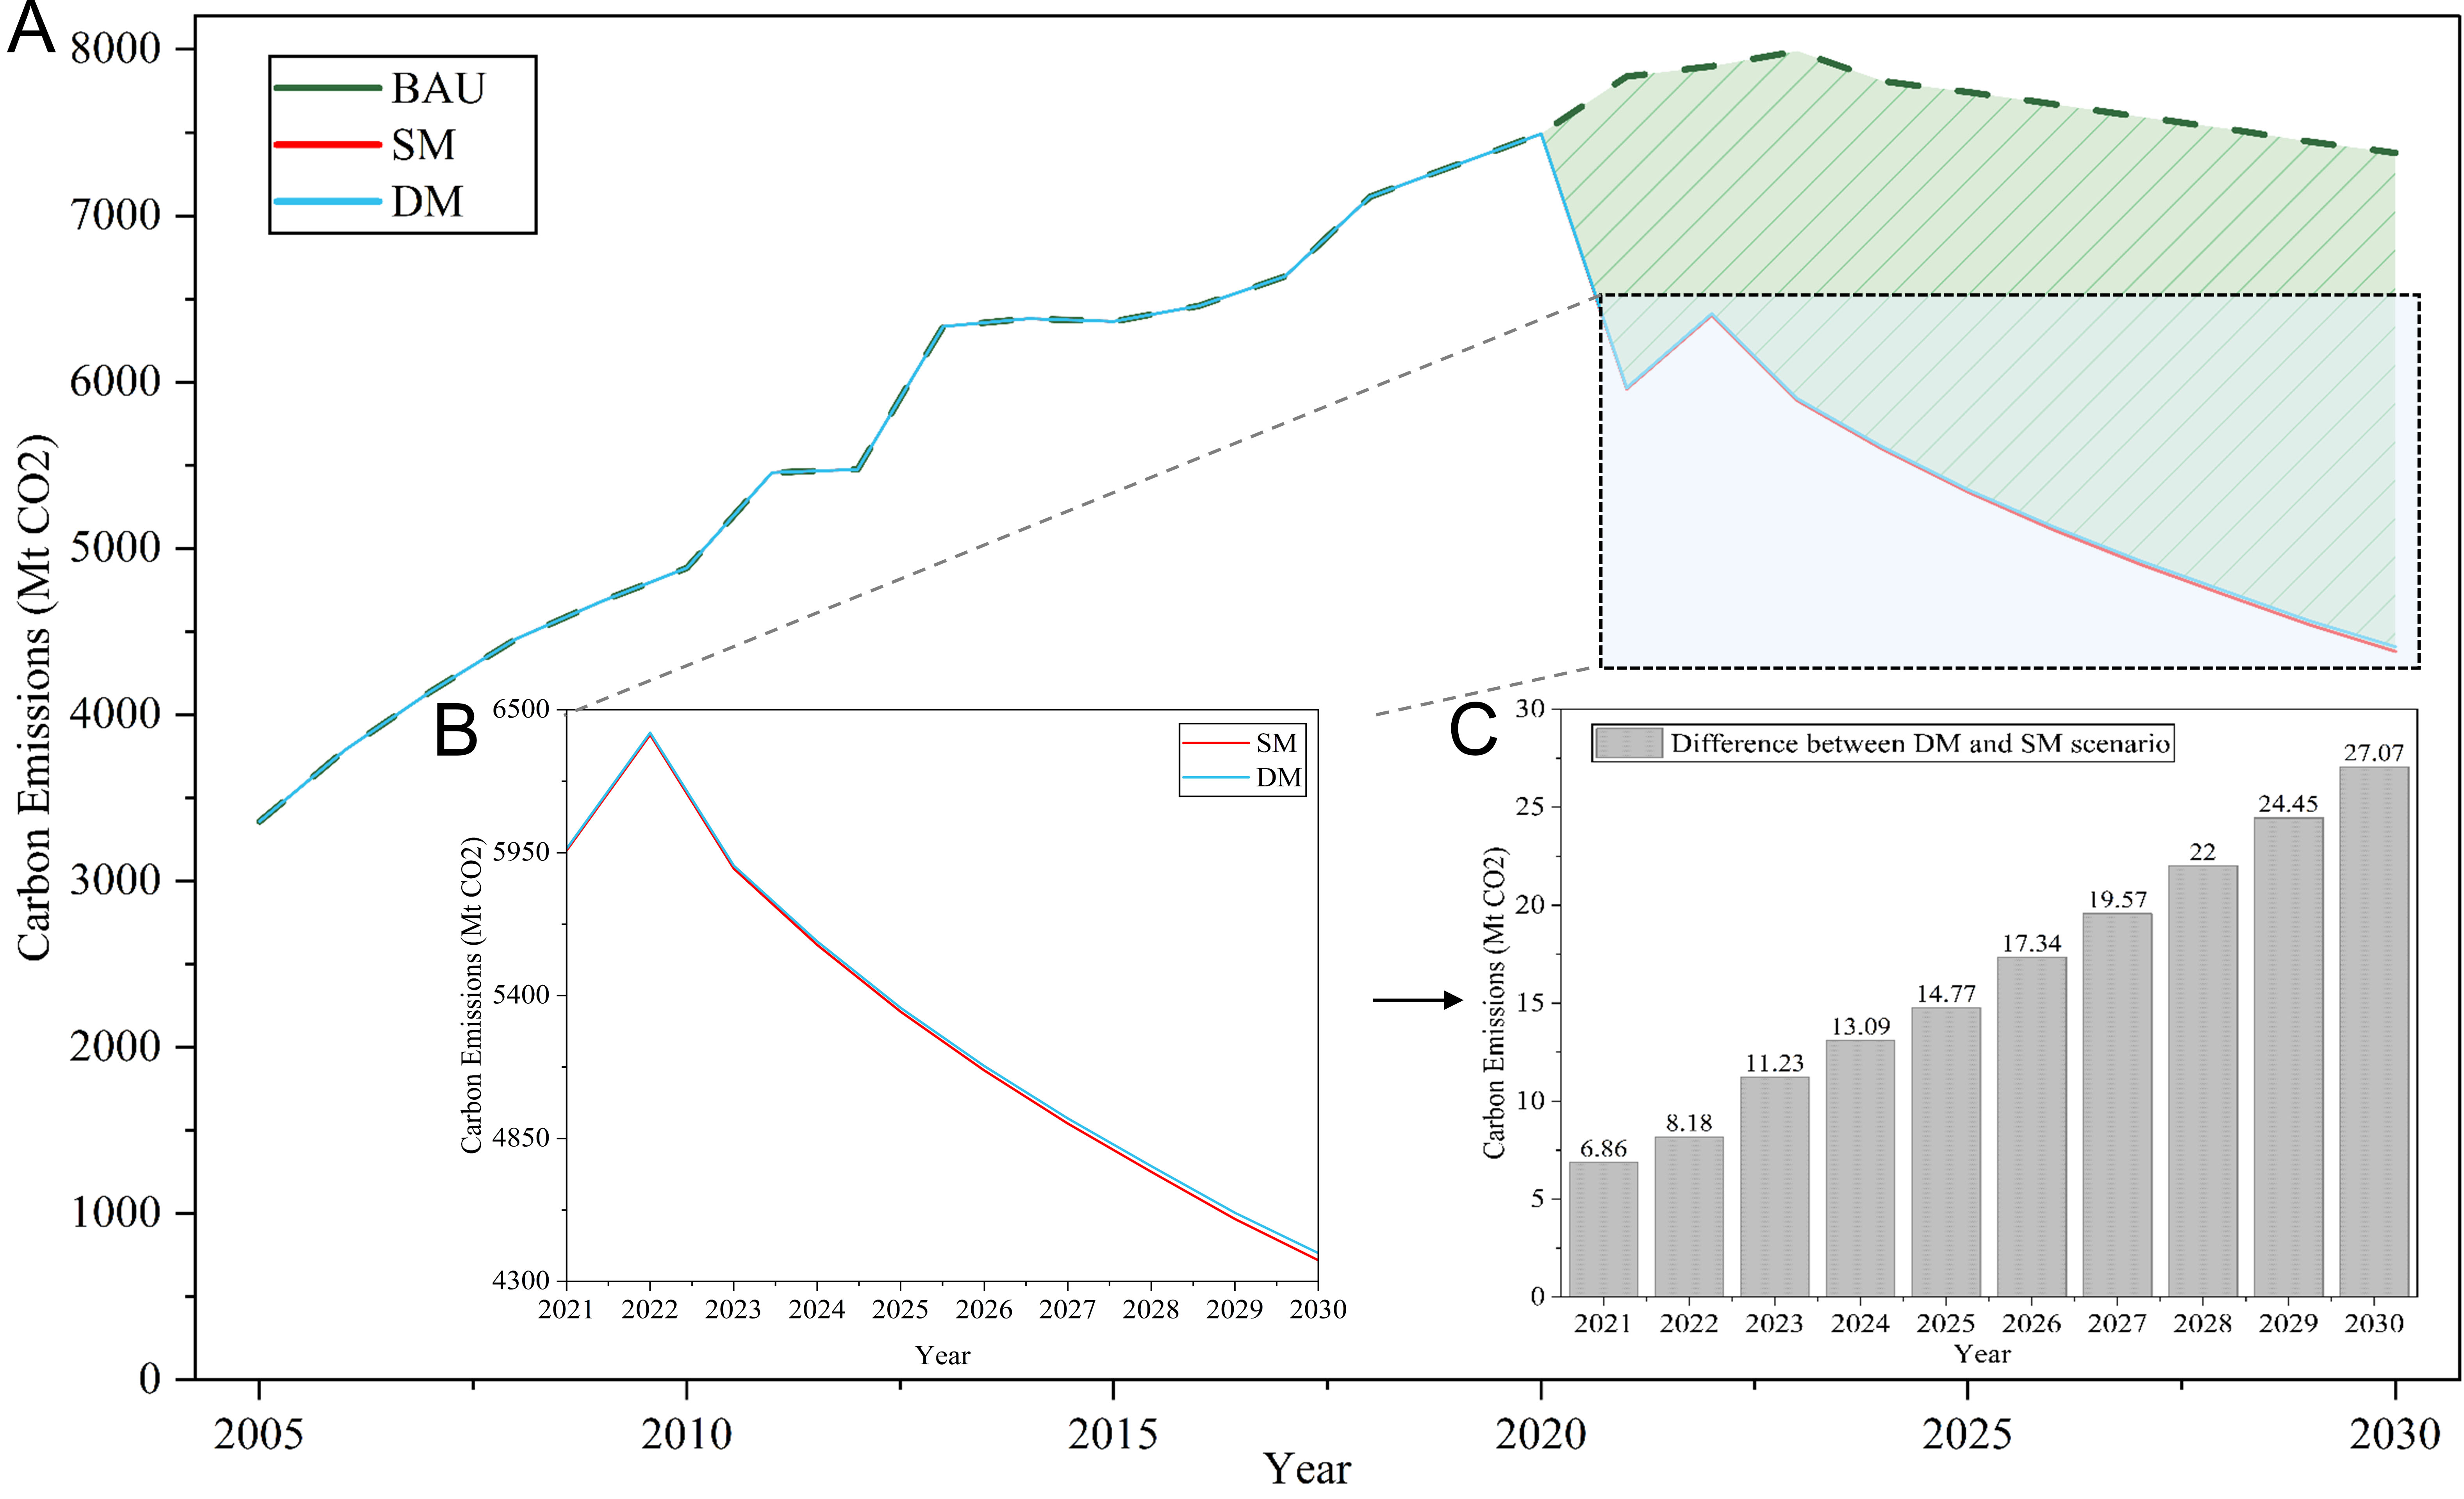
Figure 8. Simulated carbon emissions of the three scenarios. (A) Trends in carbon emissions of BAU, SM and DM scenarios from 2005 to 2030; (B) Enlarged view of SM and DM emissions during the simulation period from 2020 to 2030; (C) Differences in emissions between DM and SM (DM minus SM). BAU is the baseline scenario with no carbon trading market. SM is the single market scenario with ETS. DM is the dual market scenario integrating ETS and CCER. CCER: China Certified Emission Reduction; ETS: China’s Emissions Trading System.
Figure 9 shows the overall energy consumption trends from 2021 to 2030 across the three scenarios. Similar to the carbon emissions trajectories, energy consumption under the BAU scenario initially rises from 3,268 Mtce to a peak of 3,360 Mtce in 2023, and then gradually declines to 3,278 million ton coal equivalent (Mtce) as energy intensity targets are progressively tightened. In contrast, total energy consumption drops to 1,965 Mtce under the Single Market scenario and to 1,977 Mtce under the Dual Market scenario by 2030, reflecting a reduction trend that emerges earlier and is more pronounced compared to the BAU scenario. The energy conservation rates in both market scenarios are approximately 40%, with energy consumption under the Dual Market scenario slightly higher than under the Single Market scenario, indicating a modest rebound after the introduction of CCER. Moreover, the four sectors exhibit heterogeneity in energy consumption reductions under the Dual Market scenario. Averaged over 2021-2030, the power generation sector accounts for 79.4% of total energy savings, making it the largest contributor. This contribution is driven by the growing share of non-fossil fuels and improvements in energy efficiency[8,56], with the energy-saving effect intensifying over time. The steel and aluminum sectors have also decreased energy consumption, with average reductions of 20.6% and 1.9% over 2021-2030, respectively, reflecting their differentiated mitigation potential and compliance pressures under the carbon market. In contrast, the cement industry exhibits a 2% rebound in energy consumption compared to the BAU scenario, attributed to the adoption of advanced production technologies and relatively lower emission intensity, which reduce industrial pressure for energy savings under the carbon trading market[56].
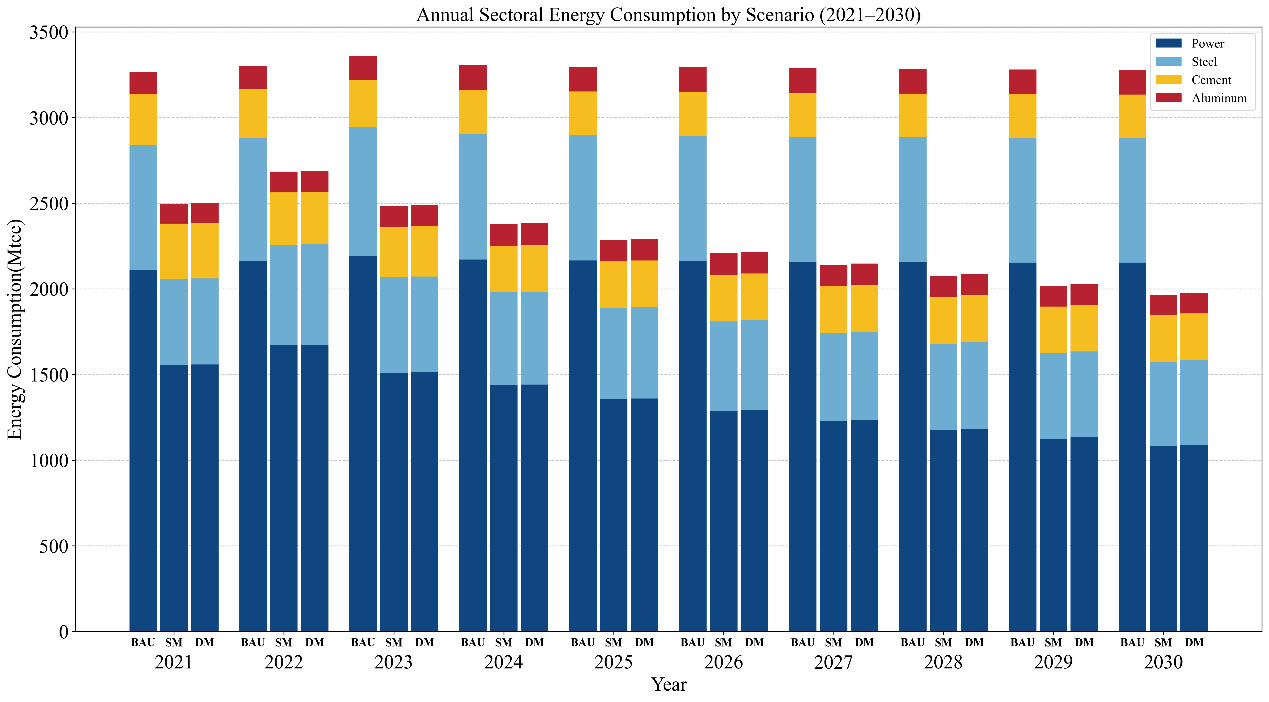
Figure 9. Trends in total energy consumption of the three scenarios. BAU is the baseline scenario with no carbon trading market. SM is the single market scenario with ETS. DM is the dual market scenario integrating ETS and CCER. CCER: China Certified Emission Reduction; ETS: China’s Emissions Trading System.
Figure 10 decomposes the 2030 energy-consumption gap between the BAU scenario and both the Single Market and Dual Market scenarios into the output channel (Y) and transaction-cost channel (φi∙C). In both comparisons, power generation accounts for the largest absolute gap, followed by steel and electrolytic aluminum, while cement exhibits a modest rebound. Under the Single Market scenario, the output channel accounts for 83.1%, 64.5%, 52.3%, and 65.6% of the sectoral gaps in power generation, steel, cement, and electrolytic aluminum, respectively. The corresponding shares under the Dual Market scenario are 83.2%, 64.7%, 52.3%, and 65.8%. In aggregate, the output and transaction-cost channels account for approximately 79.9% and 20.1% of the BAU-SM gap, and 80.0% and 20.0% of the BAU-DM gap, respectively. This consistent dominance of the output channel indicates that sectoral output adjustment is the primary mechanism through which both carbon-market scenarios affect aggregate energy consumption. The slightly smaller contribution of the transaction-cost channel under Dual Market shows that introducing CCER reduces effective transaction costs and consequently weakens the suppressive effect on energy consumption.
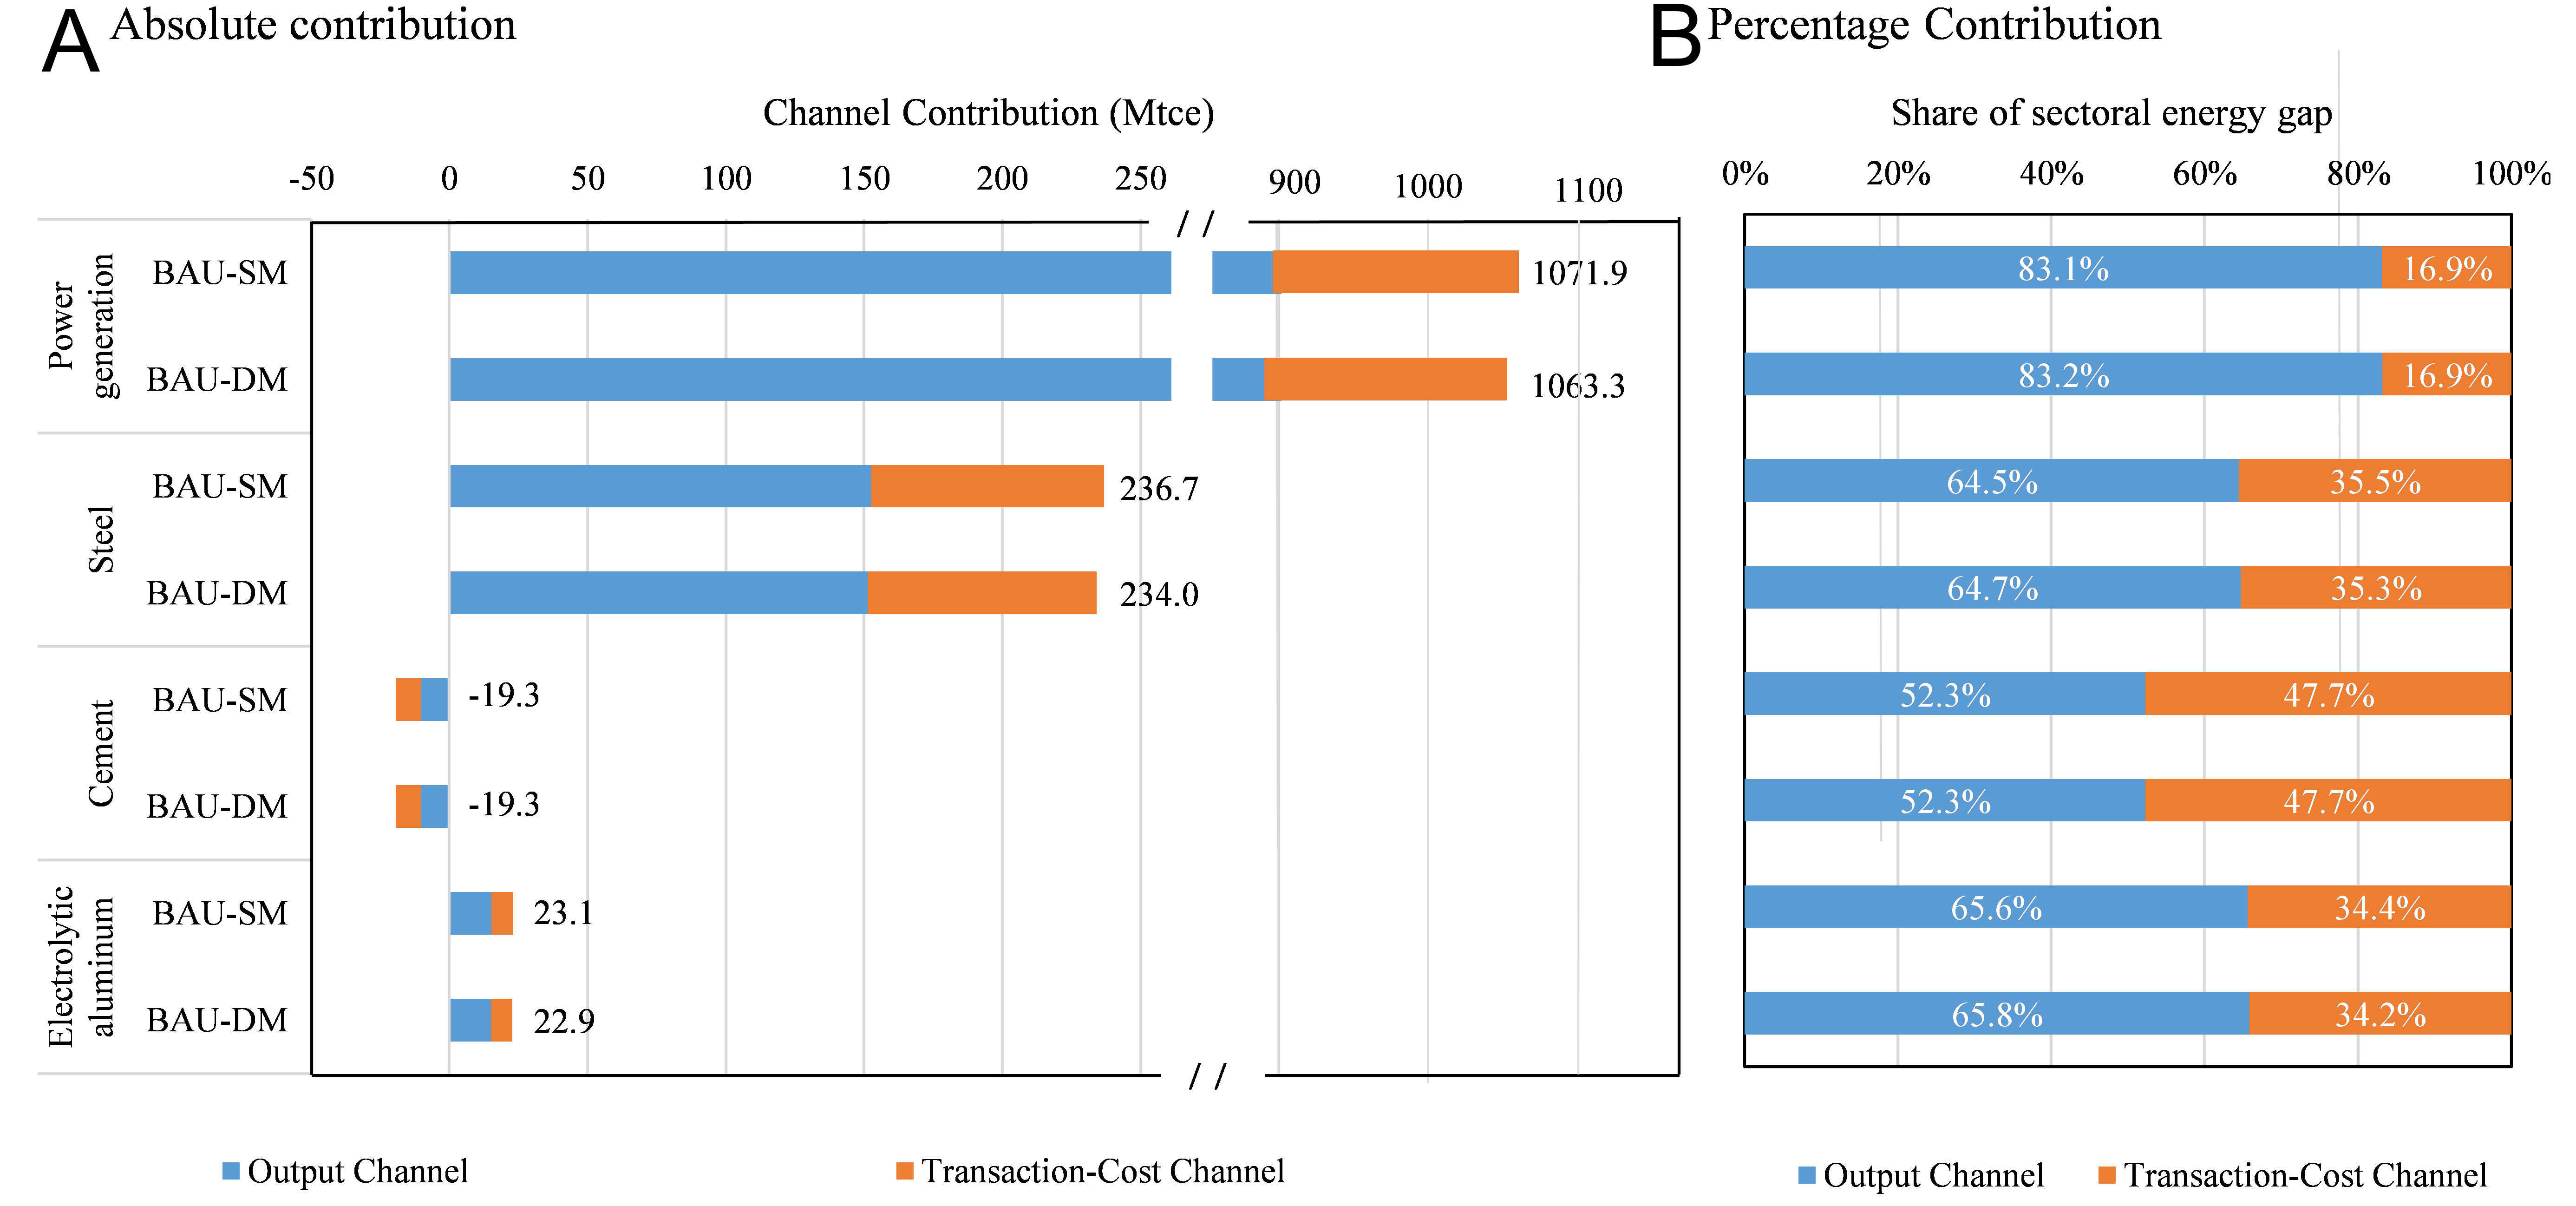
Figure 10. Sectoral decomposition of the 2030 energy-consumption gap between the BAU scenario and both SM and DM scenarios. (A) presents the absolute contributions of the output channel and transaction cost channel in each sector; (B) presents the percentage contribution of each channel to the corresponding sectoral energy gap. Positive values indicate energy savings under SM and DM, while negative values indicate an energy-consumption rebound. Owing to floating-point arithmetic limitations, the sum may deviate slightly from unity. BAU is the baseline scenario with no carbon trading market. SM is the single market scenario with ETS. DM is the dual market scenario integrating ETS and CCER. CCER: China Certified Emission Reduction; ETS: China’s Emissions Trading System.
Comparisons of economic and industrial employment
Figure 11 presents GDP and sectoral output trajectories under the three scenarios from 2020 to 2030. Under the BAU scenario, GDP increases steadily from CNY 101.4 trillion in 2020 to CNY 177.4 trillion in 2030. GDP also rises under both Single Market and Dual Market scenarios but remains approximately 1.6% below the BAU level by 2030. This difference mainly reflects carbon-market compliance costs, which constrain output growth in regulated industries. GDP under the Dual Market scenario is 0.001%-0.013% higher than under the Single Market scenario, indicating that CCER provides additional compliance flexibility and marginally mitigates the adverse economic effects of the ETS[57]. At the sectoral level, output in all four sectors expands under the BAU scenario. Under Single Market and Dual Market scenarios, output declines in power generation, steel, and electrolytic aluminum sectors, whereas cement output increases moderately. The contraction is most pronounced in power generation because of its high emissions and correspondingly strong compliance demand. By contrast, the increase in cement output reflects its relatively limited emission reduction burden[56].
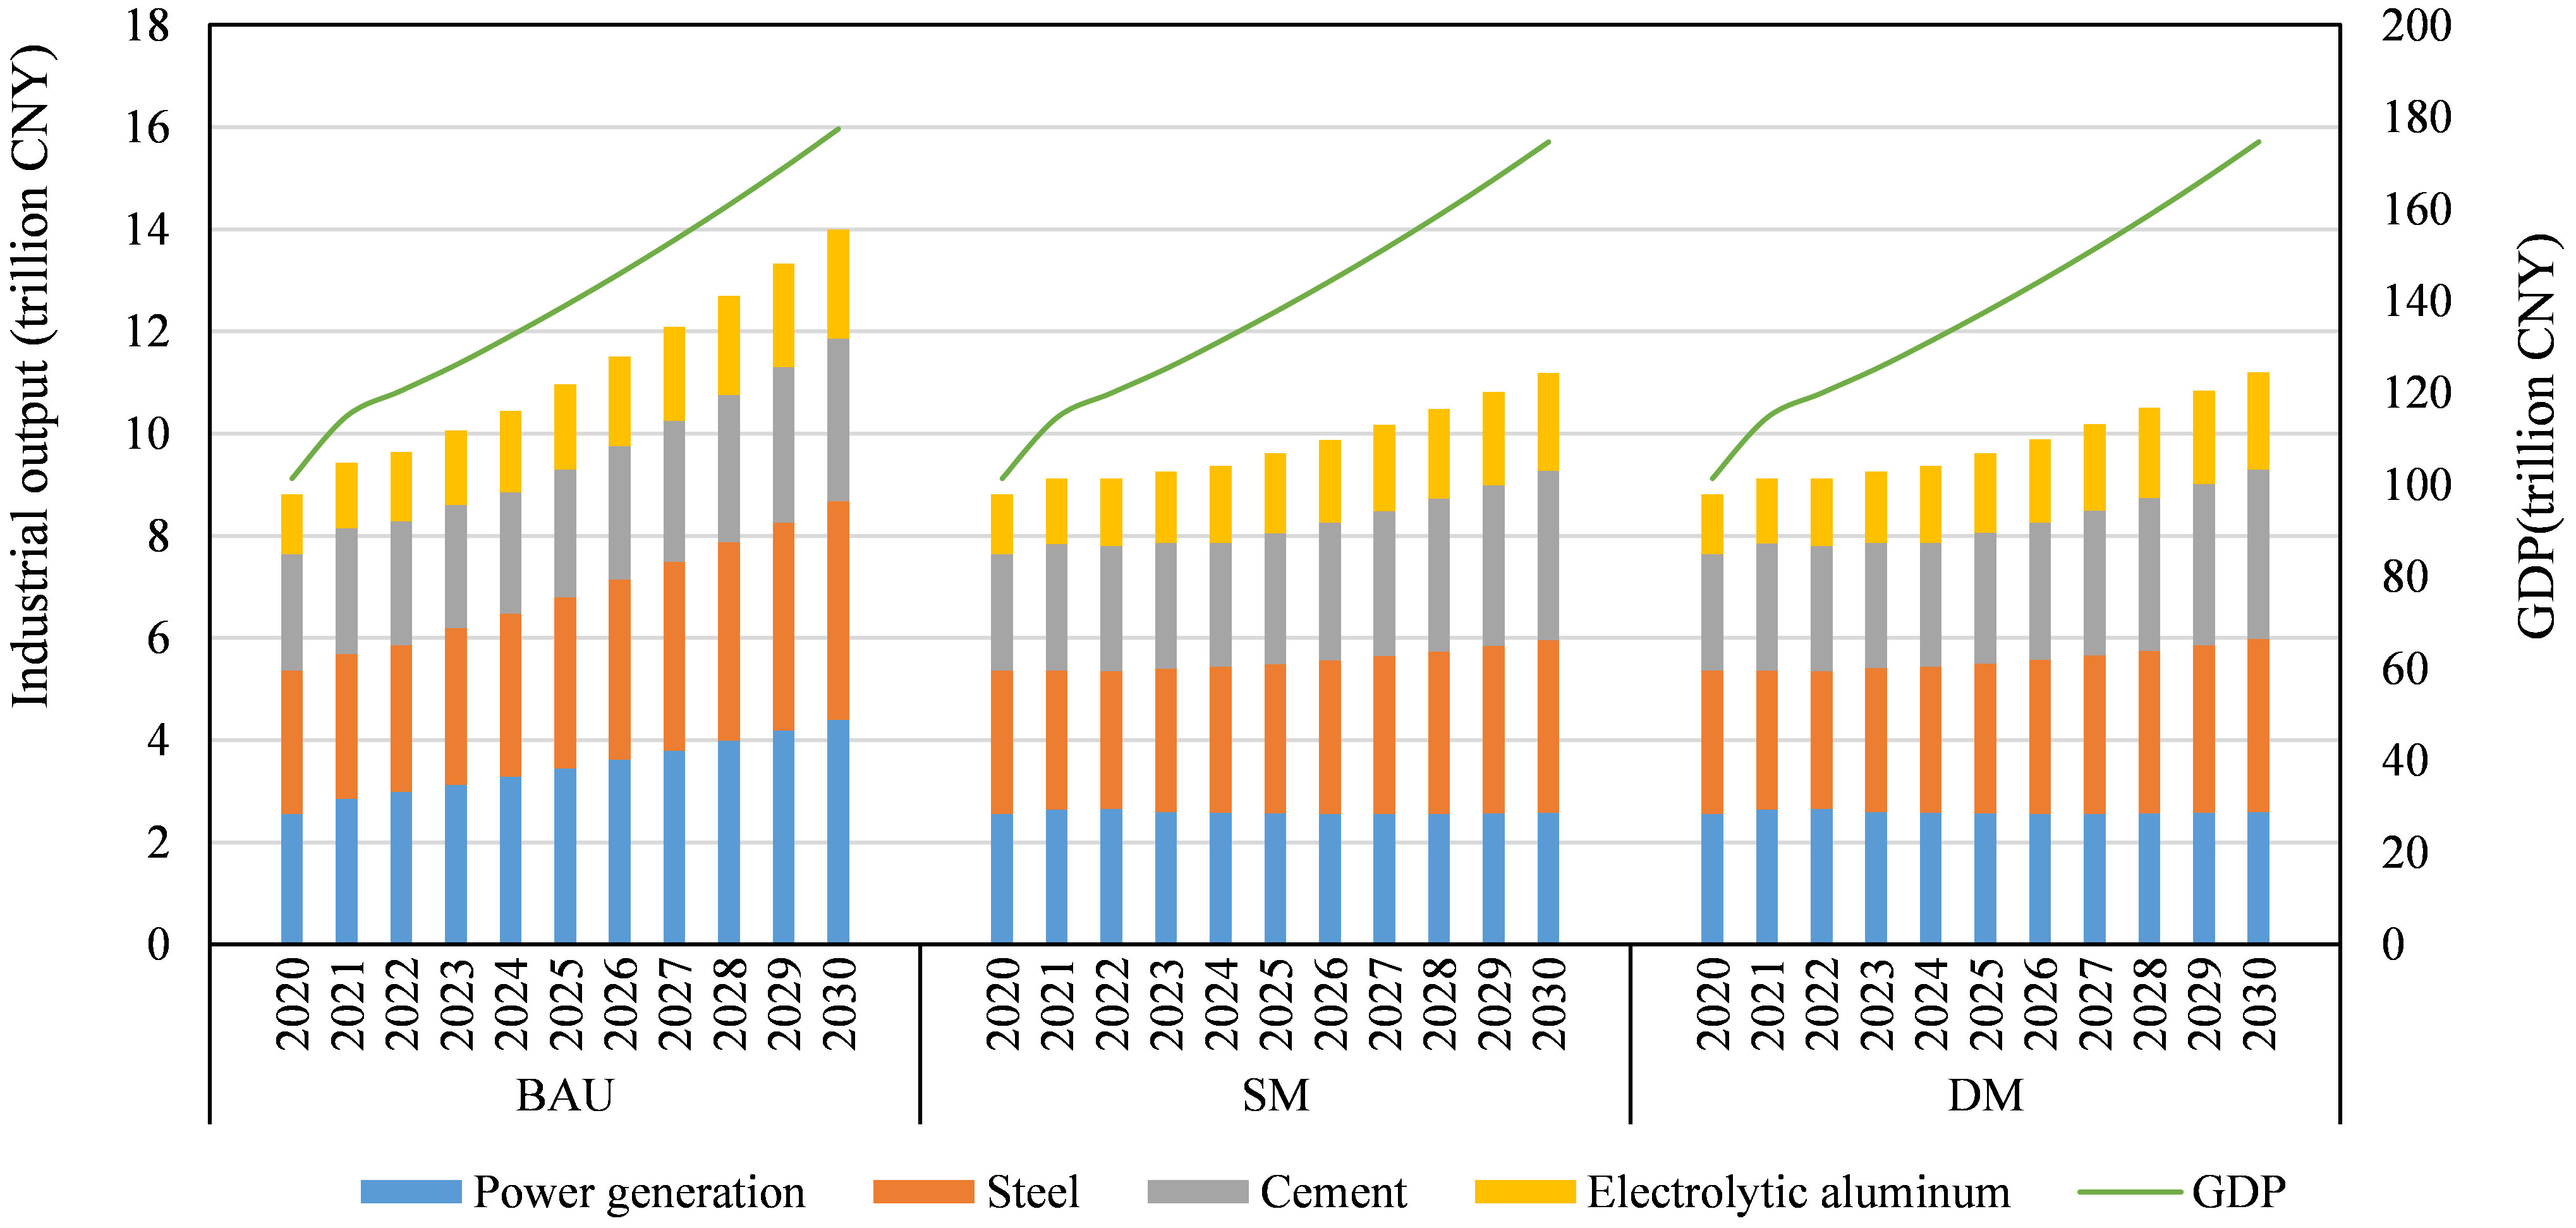
Figure 11. Trends in GDP and sectoral output under the three scenarios. The outputs of power generation, steel, cement, and electrolytic aluminum are presented as stacked bars, while the outputs of other industries are included in the aggregate GDP calculation. BAU is the baseline scenario with no carbon trading market. SM is the single market scenario with ETS. DM is the dual market scenario integrating ETS and CCER. GDP: Gross domestic product; CCER: China Certified Emission Reduction; ETS: China’s Emissions Trading System.
In this study, the unit abatement cost is calculated as the transaction cost divided by the amount of emission reduction. Transaction cost is defined as the direct expenditure on purchasing allowances and CCERs for compliance. Table 5 shows the unit abatement costs under the Single Market scenario and the Dual Market scenario, revealing a consistent downward trend in both cases. In the Single Market scenario, the unit cost decreases by 64.7%, from CNY 170.57 per ton in 2021 to CNY 60.16 per ton in 2030. Similarly, the Dual Market scenario shows a reduction from CNY 170.55 per ton to CNY 59.75 per ton over the same period, representing a decrease of 65.0%. The unit abatement cost under the Dual Market scenario is consistently lower than under the Single Market scenario, with the cost-saving advantage widening overall. The cost saving widens from CNY 0.02 per ton in 2021 to CNY 0.41 per ton in 2030, indicating enhanced cost-effectiveness of the CCER mechanism within the coupled market framework.
Unit abatement costs and differences in Single Market and Dual Market scenarios
| Year | Single market (CNY/ton) | Dual market (CNY/ton) | Cost saving (CNY/ton) |
| 2021 | 170.57 | 170.55 | 0.02 |
| 2022 | 124.58 | 124.43 | 0.15 |
| 2023 | 121.68 | 121.60 | 0.08 |
| 2024 | 103.29 | 103.16 | 0.13 |
| 2025 | 92.10 | 91.97 | 0.14 |
| 2026 | 83.19 | 82.99 | 0.20 |
| 2027 | 75.63 | 75.38 | 0.24 |
| 2028 | 69.54 | 69.24 | 0.30 |
| 2029 | 64.60 | 64.25 | 0.35 |
| 2030 | 60.16 | 59.75 | 0.41 |
Figure 12 illustrates the employment effects under dual market scenarios. Total employment in the modeled sectors under the Dual Market scenario is 0.68 million lower than under BAU in 2021, with this gap widening to 4.59 million by 2030. The decline is concentrated in the steel and power sectors, where employment decreases by 2.89 million and 1.89 million, respectively, reflecting the contraction in labor demand induced by output adjustments in carbon-intensive industries. Nevertheless, compared with the Single Market scenario, the Dual Market scenario reduces employment losses, preserving a cumulative total of 0.19 million. This modest improvement suggests that CCER provides regulated entities with greater compliance flexibility and reduces adjustment costs, thereby alleviating the impact of carbon trading constraints on the output and labor demand of high-carbon industries[57].
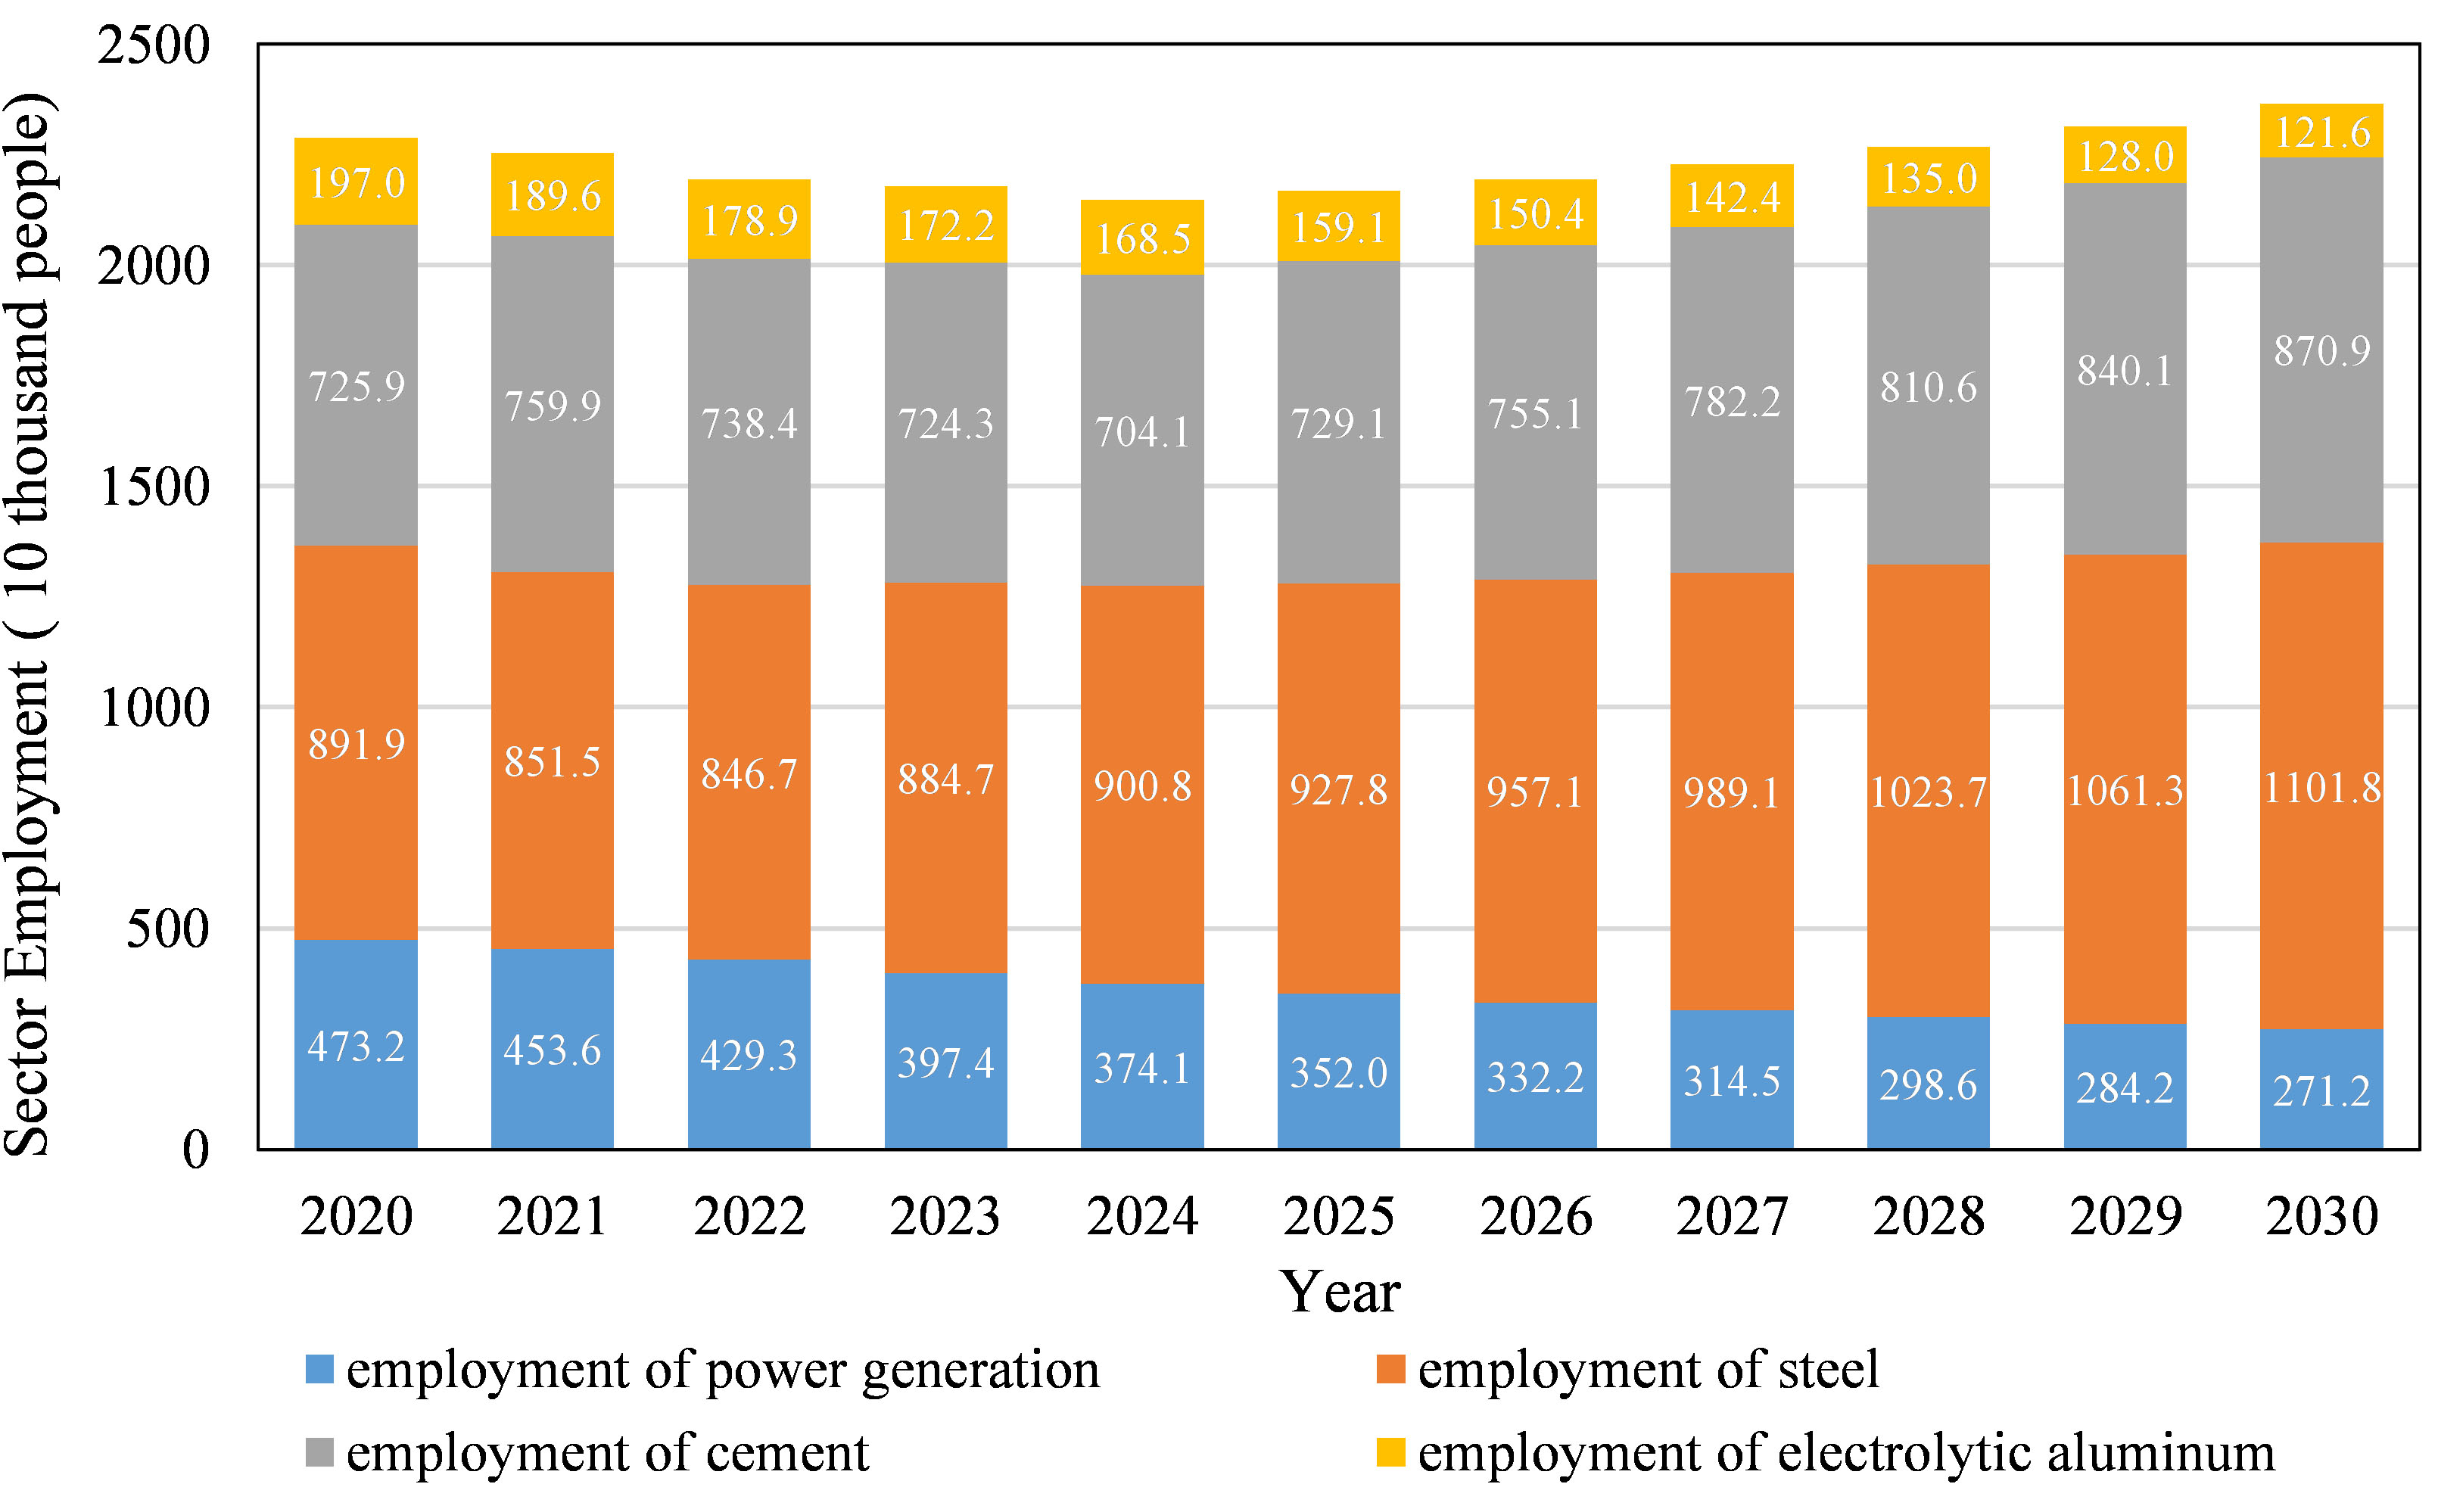
Figure 12. Trends in employment of DM scenario. DM is the dual market scenario integrating ETS and CCER. CCER: China Certified Emission Reduction; ETS: China’s Emissions Trading System.
Comparison of sectoral transaction behavior
Figure 13 presents CCER transaction volumes across sectors from 2020 to 2030. It shows that overall CCER transaction volume initially increases and declines at the end of the simulation period, potentially reflecting longer-term structural adjustments associated with carbon trading policies. The power generation sector consistently dominates the CCER trading market, with its transaction share increasing from 59.2% in 2020 to 59.5% in 2030. This reflects its large emission scale, significant abatement potential, and high compliance demand, identifying the power sector as the largest buyer and principal source of demand for CCER[40]. The proportion of CCER transactions in the steel industry decreased from 34.4% in 2020 to 32.3% in 2030, consistent with projections that structural adjustments and demand-side moderation may gradually weaken the role of the steel sector in the carbon markets[58]. The aluminum sector shows a similar upward trend in CCER transaction volume as the power generation sector, increasing by 1.8 percentage points over the decade, primarily driven by rising production output and associated carbon emissions. In contrast, the cement industry has become a net seller of allowances. This is because the accelerated decarbonization progress in the cement industry has significantly reduced its carbon emission intensity[59,60], generating a surplus of allowances under intensity-based benchmark allocation.
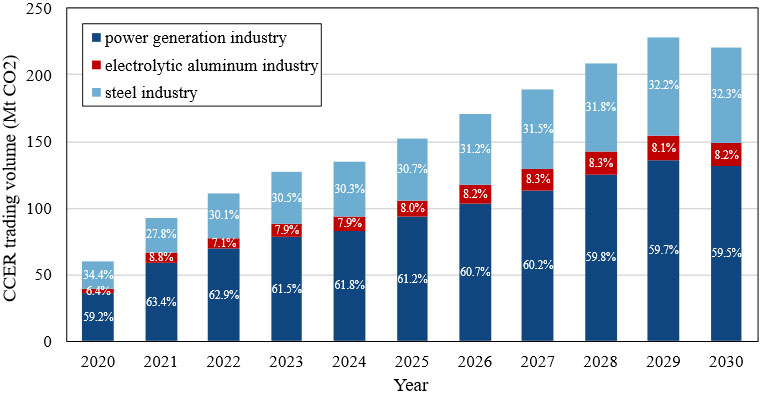
Figure 13. CCER transaction volumes associated with sectoral compliance obligations for emissions generated during 2020-2030. CCER: China Certified Emission Reduction.
While CCER transactions provide compliance flexibility across sectors, the environmental integrity of CCER used for offsets is important for evaluating whether coupling CCER with the ETS genuinely delivers additional emission reductions. The certification rate in this model primarily represents the proportion of potential emission reductions that become eligible CCER, rather than the comprehensive measure of environmental integrity. In practice, environmental integrity depends on additionality assessment, credible baseline setting, robust monitoring and verification, and the avoidance of double counting[32-34]. Therefore, the effectiveness of the voluntary carbon market in reducing emissions also requires consideration of the quality of carbon credits.
Sensitivity analysis
In order to evaluate the robustness of the simulation results and identify key carbon market policy parameters influencing the environmental and economic benefits, this study conducts a sensitivity analysis by adjusting six critical factors around the dual-market baseline (S1) [Table 6]. (1) Allowance price (S2-S3): ranging from CNY 85 to 125 per ton (-15% to +25% relative to the baseline price of CNY 100 per ton); (2) Free allocation ratio (S4-S5): set at 90% and 50% (compared to the baseline of 95%); (3) CCER certification rate (S6-S7): set at 20% and 40%, reflecting different levels of regulatory stringency[39]; (4) CCER offset rate (S8-S9): adjusted to 10% to evaluate flexibility of CCER[61], with S9 also setting the CCER certification rate to 40%; (5) CCER price (S10-S13): ranging from CNY 65 to 125 per ton (S10-S12), while S13 jointly increases the allowance and CCER prices to CNY 125 per ton; (6) Coefficient φi (S14-S15): decreased by 5% and 10% respectively, reflecting a potential weakening of sectoral energy consumption responses to carbon-cost signals during the low-carbon transition.
Scenario settings for sensitivity analysis
| Scenario | Allowance price | Free allocation ratio | CCER price | Offset rate | Certification rate | Adjustment coefficient change of φ |
| S1 | 100 | 95% | 80 | 5% | 30% | 0% |
| S2 | 85 | 95% | 80 | 5% | 30% | 0% |
| S3 | 125 | 95% | 80 | 5% | 30% | 0% |
| S4 | 100 | 90% | 80 | 5% | 30% | 0% |
| S5 | 100 | 50% | 80 | 5% | 30% | 0% |
| S6 | 100 | 95% | 80 | 5% | 20% | 0% |
| S7 | 100 | 95% | 80 | 5% | 40% | 0% |
| S8 | 100 | 95% | 80 | 10% | 30% | 0% |
| S9 | 100 | 95% | 80 | 10% | 40% | 0% |
| S10 | 100 | 95% | 65 | 5% | 30% | 0% |
| S11 | 100 | 95% | 90 | 5% | 30% | 0% |
| S12 | 100 | 95% | 100 | 5% | 30% | 0% |
| S13 | 125 | 95% | 125 | 5% | 30% | 0% |
| S14 | 100 | 95% | 80 | 5% | 30% | -5% |
| S15 | 100 | 95% | 80 | 5% | 30% | -10% |
Figure 14 illustrates the sensitivity analysis results. From a single-factor perspective, the allowance price, free allocation ratio, and CCER price significantly influence carbon emissions and transaction costs. In the short term, changes in carbon market policies mainly influence the production and energy-use decisions of carbon-intensive industries, while over the longer term these behavioral adjustments accumulate and translate into sustained reductions in carbon emissions[62]. Specifically, a 15% decrease in the allowance price (S2) reduces transaction costs by 6.2% and increases GDP by 0.14%, but leads to a 5.4% rebound in emissions, whereas a high allowance price generally reduces emissions (S3). Furthermore, reducing the free allocation ratio from 95% to 90% (S4) and 50% (S5), carbon emissions decreased by 2.7% and 21.8% respectively. This shift toward auctioning enhances allocation efficiency through clearer price signals, but also increases firms’ cost burden[63], resulting in GDP declines of 0.08% and 0.69% in the two scenarios. Regarding the CCER price, convergence with the allowance price (S12) stimulates CCER supply and carbon market trading. However, excessively high allowance and CCER prices (S13) lead to changes in transaction costs ranging from -2.3% to 25.5% and reductions in carbon emissions of 1.3%-8.7% over the simulation period, highlighting the importance of maintaining price stability and differentiation between both markets to preserve the cost-effectiveness of the CCER. In contrast, variations in the CCER certification rate and offset rate have relatively modest impacts on carbon emissions and transaction costs outcomes, yet the results remain robust, indicating their potential influence on cost-effectiveness. From a multi-factor interaction perspective, a coordinated increase in the CCER certification rate and offset rate (S9) expands CCER availability and strengthens cost containment, indicating that higher offset flexibility is more effective when accompanied by stricter credit supply governance[39]. A lower coefficient (S15) weakens the energy-demand response to transaction costs, generating a potential rebound effect in which increased energy consumption partly offsets the emission-reduction benefits of energy-structure improvement and raises compliance costs[64].
Figure 14. Sensitivity of CO2 emissions and transaction costs to parameter changes relative to the dual-market baseline (S1). (A) allowance or CCER price change separately; (B) free allocation ratio; (C) CCER certification rate; (D) CCER offset rate; (E) joint changes in allowance and CCER prices; (F) adjustment coefficient φ. Within each group, the left and right plots show emissions and transaction costs, respectively. CCER: China Certified Emission Reduction.
Across most sensitivity scenarios, the coupled market consistently reduces firms’ compliance costs relative to the single market, although this cost advantage is generally accompanied by a modest increase in emissions. The result suggests that CCER mainly function as a lower-cost compliance option, partially substituting for firms’ internal abatement, and this trade-off becomes more pronounced when CCER is more price-competitive or more readily available.
In addition, the results indicate that excessively high carbon prices or overly stringent market policies may increase transaction costs and weaken market stability, causing short-term fluctuations[65]. These dynamics arise from the nonlinear transmission of carbon market policy parameters through price signals, trading constraints, and time lags, which may temporarily amplify volatility in compliance demand and speculative trading. Over the longer term, investment may gradually shift toward low-carbon and innovative technologies, contributing to more stable mitigation and compliance behavior among regulated firms[66].
CONCLUSION
Conclusions
As global efforts to mitigate climate change and reduce greenhouse gas emissions increasingly rely on both compliance and voluntary carbon markets, the coupling of these two schemes has emerged as a critical priority for policymakers and academic researchers. This study develops an SD model featuring dynamic feedback loops to simultaneously incorporate China’s ETS and CCER scheme, examines the comprehensive environmental and economic effects, and identifies the most influential parameters for effective policy design. The main conclusions are summarized as follows:
Firstly, coupling the CCER scheme with the ETS achieves emission reductions and energy savings nearly equivalent to those under the ETS-only scheme. By 2030, carbon emissions under the Single Market and Dual Market scenarios are projected to reach 4,381.46 Mt and 4,408.53 Mt, respectively, representing reductions of 40.6% and 40.3% relative to the BAU scenario. Likewise, energy consumption is projected to decline to 1,965 Mtce and 1,977 Mtce under the two scenarios, corresponding to energy savings of 40.1% and 39.7% versus the BAU scenario. Although the Dual Market scenario yields marginally lower environmental performance than the Single Market scenario, it significantly enhances market flexibility by enabling additional abatement transactions across voluntary mechanisms. Moreover, the CCER scheme improves cost-effectiveness. The unit abatement cost decreases significantly in both scenarios, but the Dual Market scenario delivers superior performance, which falls from CNY 170.55 to 59.75 per ton of CO2-equivalent (a reduction of 65.0%). Critically, the unit abatement cost advantage of the Dual Market scenario widens over time - from CNY 0.02 to 0.41 per ton - highlighting its growing efficiency edge. The employment results further reveal that market coupling can enhance the socio-economic resilience. Employment declines in both scenarios, but the Dual Market scenario reduces cumulative employment losses by around 190,000 jobs relative to the Single Market scenario, primarily in the steel and power sectors.
Furthermore, significant heterogeneity exists across the four sectors in terms of their carbon market transaction profiles. The power sector emerges as the predominant buyer in the CCER market, accounting for 59.5% of the total transaction volume in 2030. This active participation aligns with its substantial contribution to energy savings, accounting for an average of 79.4% of the total energy savings over the 2021–2030 period, thereby driving considerable emission abatement. The steel sector follows, comprising 32.3% of CCER transactions and contributing 20.6% to overall energy conservation. The aluminum industry shows moderate market involvement, with an 8.2% share in transaction volume and a relatively limited energy-saving impact of 1.9%. The cement sector, however, operates primarily as a net seller of carbon allowances - reflecting its more advanced decarbonization progress and lower carbon intensity. This seller status mitigates its direct compliance pressure within the carbon market and is accompanied by a marginal rebound in energy consumption.
Finally, the allowance price, free allocation ratio, and CCER price are identified as the most influential policy parameters in the coupled market scheme. A higher allowance price reduces carbon emissions by 7.54% but reduces GDP by 0.6%, while a lower allowance price leads to a 5.4% rebound in emissions. Reducing the free allocation ratio from 95% to 50% enhances carbon emission reductions by 21.8%, while reducing GDP by 0.69%. As for the CCER price, a reasonable price gap compared to the allowance price supports market liquidity, yet an excessively high price undermines its cost-saving advantage. From a multifactor perspective, the coordinated design of the CCER certification rate and offset rate is critical to balancing supply and demand while improving cost-effectiveness. Although adjustments to individual parameters produce limited effects, their combined optimization can expand CCER supply and enhance cost control, provided that stringent monitoring and verification mechanisms ensure environmental integrity.
Policy implications
Firstly, the free allocation ratio should be tailored to the development stage of the carbon market and the decarbonization capacities of different sectors. Initially, a rate of 95% is recommended to ensure stable progress in emission reductions, which can then be gradually lowered to 90%. Sensitivity analysis indicates that an excessively high share of paid allocation may suppress economic growth. Given its high abatement potential and strong allowance demand, the power sector should be prioritized for paid allocation, with a more concrete timeline or phased pathway. Specifically, the free allocation ratio could be reduced from 95% to 93% by 2027 and further to 90% by 2030. Subsequently, other high-emission sectors such as steel and aluminum could be phased in, with differentiated free allocation ratios determined according to mitigation potential, compliance costs, and sectoral characteristics. This dynamic adjustment helps balance mitigation incentives with cost containment, mitigates economic volatility, and supports the formulation of sector-specific decarbonization strategies.
Second, the CCER offset rate should be adjusted dynamically and cautiously in coordination with stringent and harmonized certification standards. A phased adjustment could be considered - from the current 5% to a maximum of 10%. Sensitivity analyses demonstrate that the joint calibration of the CCER offset rate and certification rate significantly affects mitigation effectiveness and macroeconomic efficiency. A moderate increase in the offset rate can help regulated entities meet compliance obligations more flexibly, thereby reducing average compliance costs without compromising environmental integrity. However, excessive reliance on offsets may weaken incentives for regulated entities to reduce emissions themselves. To sustainably expand the supply of high-quality projects, a dynamic certification mechanism - coupled with periodic, evidence-based adjustments to the benchmark offset rate - is essential. This dual-track approach not only enhances market liquidity and incentivizes the entry of rigorously verified emission reduction projects but also supports long-term supply-demand equilibrium in the CCER market. Crucially, such flexibility must be anchored by progressively tightening emissions caps, robust monitoring, reporting, and verification (MRV) protocols, and enforceable quality assurance measures.
Third, establish a coordinated price mechanism between the ETS and CCER schemes. Sensitivity analysis indicates that persistent price disparities - either excessively wide or unduly narrow - can impair market functionality: wide gaps risk undermining CCER project viability and distorting allowance price signals, whereas narrow gaps erode the cost-efficiency advantage of CCERs and weaken incentives for high-quality mitigation projects. Previous research shows that achieving homogeneity and equivalence between carbon allowances and CCERs is a prerequisite for effective emission-reduction efforts, given differences in allowance scarcity, offset availability, and abatement costs[22,40]. To address this, China requires a rational, rules-based price framework grounded in three empirically verifiable pillars: (1) real-time supply-demand dynamics in both markets; (2) verified abatement costs across project types; and (3) the relative scarcity of tradable allowances vs. CERs. Such a framework is critical not only for safeguarding carbon market stability and ensuring inter-sectoral fairness but also for accelerating progress toward nationally determined emission reduction targets.
Finally, reinforce long-term policy coordination between renewable energy development, green finance, and broader energy transition initiatives. While coupling markets may reduce short-term compliance costs, it could significantly influence firms’ long-term investment decisions and sector-level decarbonization trajectories, with potential implications for socio-economic stability. The sensitivity analysis further suggests that changes in the energy structure may alter the transmission of carbon-cost signals to energy consumption, and a cleaner energy structure may lead to rebounds in energy consumption, carbon emissions, and transaction costs. Therefore, enhancing synergies between the carbon market and complementary policies is critical for delivering clear and consistent policy signals to effectively facilitate long-term greenhouse gas (GHG) emissions reductions and energy transition goals while maintaining the stability of the socio-economic system. For example, integrating carbon market policy with green finance could incentivize firms’ low-carbon investments and support the transition and reskilling of workers in traditional carbon-intensive industries, thereby facilitating a steady economic transition, while aligning the carbon market with the phased retirement of coal-fired power plants can promote a just transition in the power sector.
Limitations and future directions
Although this paper enriches the study of voluntary carbon market and market-based instrument synergy from a national perspective, some limitations warrant further investigation. Firstly, the framework could be extended by incorporating industry-specific technological progress and the dynamic evolution of CCER methodologies. In particular, future studies could consider technology learning effects and differentiated CCER offset ratios with tailored retirement rules to better reflect the evolving characteristics of low-carbon technologies and carbon credit generation. In addition, future studies can incorporate more differentiated credit-quality assumptions to present the potential CCER integrity risks, such as insufficient additionality, baseline uncertainty, or double counting. Second, as China’s ETS continues to expand, future research could extend the analysis to additional industries such as aviation and transportation, thereby providing a more comprehensive assessment of carbon market performance across regulated sectors. Lastly, beyond the interaction between the compliance and voluntary carbon markets, future research could further investigate the coordination among multiple market mechanisms and policy instruments, such as green certificates, renewable electricity markets, and renewable energy incentives, to evaluate their systemic effects on emissions reduction, market efficiency, and long-term policy effectiveness.
DECLARATIONS
Authors’ contributions
Methodology: Zhu, T.
Data curation: Zhu, T.; Zeng, A.
Formal analysis: Zhu, T.
Software: Zhu, T.
Visualization: Zhu, T.
Writing - original draft: Zhu, T.
Conceptualization: Zeng, A.
Supervision: Zeng, A.
Project administration: Zeng, A.
Writing - review & editing: Zeng, A.; Zhu, K.W.; Guo, Z.
Availability of data and materials
The original contributions presented in this study are included in the article/Supplementary Materials. Further inquiries can be directed to the corresponding author.
AI and AI-assisted tools statement
During the preparation of this manuscript, the AI tool GPT (GPT-5.6 Sol, released 2026-07-09) was used solely for language editing. The tool did not influence the study design, data collection, analysis, interpretation, or the scientific content of the work. All authors take full responsibility for the accuracy, integrity, and final content of the manuscript.
Financial support and sponsorship
We are grateful for financial support provided by the National Natural Science Foundation of China (No. 72604423).
Conflicts of interest
All authors declared that there are no conflicts of interest.
Ethical approval and consent to participate
Not applicable.
Consent for publication
Not applicable.
Copyright
© The Author(s) 2026.
Supplementary Materials
REFERENCES
1. Intergovernmental Panel on Climate Change (IPCC). Climate Change 2023: Synthesis Report. 2023. Available from: https://www.ipcc.ch/report/ar6/syr/downloads/report/IPCC_AR6_SYR_LongerReport.pdf (accessed 2026-10-26).
2. Ding, S.; Zhang, M.; Song, Y. Exploring China’s carbon emissions peak for different carbon tax scenarios. Energy. Policy. 2019, 129, 1245-52.
3. International Carbon Action Partnership. Emissions Trading worldwide: Status Report 2026. 2026 Available from: https://icapcarbonaction.com/system/files/document/260610_ICAP_SR26_Web.pdf (accessed 2026-10-26).
4. Blaufelder, C.; Levy, C.; Mannion, P.; Pinner, D. A blueprint for scaling voluntary carbon markets to meet the climate challenge. McKinsey Report 2021, 1, 2-7. https://www.mckinsey.com/~/media/mckinsey/business%20functions/sustainability/our%20insights/a%20blueprint%20for%20scaling%20voluntary%20carbon%20markets%20to%20meet%20the%20climate%20challenge/a-blueprint-for-scaling-voluntary-carbon-markets-to-meet-the-climate-challenge.pdf?shouldIndex (accessed 2026-10-26).
5. Tan, X.; Guo, W.; Fan, J.; et al. Policy framework and technology innovation policy of carbon peak and carbon neutrality. Bull. Chin. Acad. Sci. 2022, 37, 435-43.
6. Ministry of Ecology and Environment the People’s Republic of China (MEEPRC). Progress Report of China’s National Carbon Market (2025). 2025. Available from: https://www.mee.gov.cn/ywgz/ydqhbh/wsqtkz/202509/W020250927515319387445.pdf (accessed 2026-10-26).
7. Fan, D.; Chen, S. No pain, no gain? Simulation of carbon reduction potential and socioeconomic effects of voluntary carbon trading in China during 2021-2060. Appl. Energy. 2024, 375, 124195.
8. Yang, S.; Mi, F. Renewable Portfolio standards, carbon emissions trading and China certified emission reduction: the role of market mechanisms in optimizing China’s Power Generation Structure. Energies 2025, 18, 894.
9. Jung, H.; Song, C. K. Effects of emission trading scheme (ETS) on change rate of carbon emission. Sci. Rep. 2023, 13, 912.
10. Gao, Y.; Li, M.; Xue, J.; Liu, Y. Evaluation of effectiveness of China’s carbon emissions trading scheme in carbon mitigation. Energy. Econ. 2020, 90, 104872.
11. Li, K.; Luo, Z.; Hong, L.; Wen, J.; Fang, L. The role of China’s carbon emission trading system in economic decarbonization: evidence from Chinese prefecture-level cities. Heliyon 2024, 10, e23799.
12. Lin, B.; Huang, C. Analysis of emission reduction effects of carbon trading: Market mechanism or government intervention? Sustain. Prod. Consump. 2022, 33, 28-37.
13. Wu, R.; Tan, Z.; Lin, B. Does carbon emission trading scheme really improve the CO2 emission efficiency? Energy 2023, 277, 127743.
14. Yan, Y.; Zhang, X.; Zhang, J.; Li, K. Emissions trading system (ETS) implementation and its collaborative governance effects on air pollution: the China story. Energy. Policy. 2020, 138, 111282.
15. Li, W.; Zhang, Y.; Lu, C. The impact on electric power industry under the implementation of national carbon trading market in China: a dynamic CGE analysis. J. Clean. Prod. 2018, 200, 511-23.
16. Xu, S.; Xu, Q. Impacts of carbon emissions allowance limitations on carbon price with power generation rights trading in China. J. Clean. Prod. 2024, 470, 143312.
17. Wang, Y.; Zhou, R. Can carbon emission trading policies promote the withdrawal of government subsidies and the green development of enterprises? Humanit. Soc. Sci. Commun. 2024, 11, 4255.
18. Zhang, L.; Li, Y.; Jia, Z. Impact of carbon allowance allocation on power industry in China’s carbon trading market: computable general equilibrium based analysis. Appl. Energy. 2018, 229, 814-27.
19. Zhang, Y.; Li, S.; Luo, T.; Gao, J. The effect of emission trading policy on carbon emission reduction: evidence from an integrated study of pilot regions in China. J. Clean. Prod. 2020, 265, 121843.
20. Shi, C.; Xian, Y.; Wang, Z.; Wang, K. Marginal abatement cost curve of carbon emissions in China: a functional data analysis. Mitig. Adapt. Strateg. Glob. Change. 2023, 28, 10047.
21. Zhang, Y.; Chen, Y.; Yang, F. The impact and mechanism of the Chinese certified emission reduction policy on carbon emission intensity. Pol. J. Environ. Stud. 2026, 35, 1469-85.
22. Li, L.; Ye, F.; Li, Y.; Chang, C. T. How will the Chinese certified emission reduction scheme save cost for the national carbon trading system? J. Environ. Manage. 2019, 244, 99-109.
23. Xie, M.; Chen, L. Private governance in climate mitigation: a global comparison of corporate participation in voluntary carbon markets. J. Comp. Policy. Anal. 2025, 27, 245-64.
24. He, Y.; Jiang, R.; Liao, N. How to promote the Chinese certified emission reduction scheme in the carbon market? A study based on tripartite evolutionary game model. Energy 2023, 285, 128723.
25. Yang, P.; Yu, L.; Wang, X.; Zheng, P.; Lv, X.; Yue, J. Multi-objective planning and optimization of microgrid lithium iron phosphate battery energy storage system consider power supply status and CCER transactions. Int. J. Hydrogen. Energ. 2022, 47, 29925-44.
26. Jia, F.; Pan, T.; He, Q.; Chen, L. The impact of China certified emission reduction market resumption on manufacturers’ stock market valuations: the role of OSCM factors. J. Clean. Prod. 2024, 472, 143467.
27. Hultman, N.; Lou, J.; Hutton, S. A review of community co-benefits of the clean development mechanism (CDM). Environ. Res. Lett. 2020, 15, 053002.
28. Wang, Q.; Chen, Y. Barriers and opportunities of using the clean development mechanism to advance renewable energy development in China. Renew. Sust. Energ. Rev. 2010, 14, 1989-98.
29. Zhang, Y.; Liu, J.; Woodward, R. T. Has Chinese certified emission reduction trading reduced rural poverty in China? Aus. J. Agri. Res. Econ. 2023, 67, 438-58.
30. Probst, B. S.; Toetzke, M.; Kontoleon, A.; et al. Systematic assessment of the achieved emission reductions of carbon crediting projects. Nat. Commun. 2024, 15, 9562.
31. Corsini, C.; Chaib, J.; Davies, M.; Centeno, D.; Feldmann, R.; Wang, H. Risk-adaptive conservation zones: integrating degradation vulnerability into spatially explicit carbon crediting. Carbon. Footprints. 2026, 5, 34.
32. Michaelowa, A.; Hermwille, L.; Obergassel, W.; Butzengeiger, S. Additionality revisited: guarding the integrity of market mechanisms under the Paris Agreement. Climate. Policy. 2019, 19, 1211-24.
33. Haya, B.; Cullenward, D.; Strong, A. L.; et al. Managing uncertainty in carbon offsets: insights from California’s standardized approach. Climate. Policy. 2020, 20, 1112-26.
34. Fuss, S.; Lamb, W. F.; Callaghan, M. W.; et al. Negative emissions - part 2: costs, potentials and side effects. Environ. Res. Lett. 2018, 13, 063002.
35. Liang, Z.; Wu, S.; He, Y.; et al. China certified emission reduction projects: historical and current status, development, and future prospects - taking forestry projects as an example. Sustainability 2025, 17, 3284.
36. Li, Z.; Yu, Z.; Zhang, P.; et al. Comparative analysis of certified emission reduction methodologies for methane emission reduction in China. J. Environ. Manage. 2025, 375, 124242.
37. Xu, S. Forestry offsets under China’s certificated emission reduction (CCER) for carbon neutrality: regulatory gaps and the ways forward. IJCCSM 2024, 16, 140-56.
38. Ye, F.; Xiong, X.; Li, L.; Li, Y. Measuring the effectiveness of the Chinese Certified Emission Reduction scheme in mitigating CO2 emissions: a system dynamics approach. J. Clean. Prod. 2021, 294, 125355.
39. Zhang, C.; Lin, B. Impact of introducing Chinese certified emission reduction scheme to the carbon market: promoting renewable energy. Renew. Energy. 2024, 222, 119887.
40. Zhang, N.; Pang; J. The economic impacts of introducing CCER trading and offset mechanism into the national carbon market of China. Adv. Clim. Change. Res. 2022, 18, 622-33.
41. Paraschiv, F.; Schmid, H.; Schmitz, M.; Dünwald, V.; Groos, E. The interplay between China’s regulated and voluntary carbon markets and its influence on renewable energy development - a literature review. Energies 2024, 17, 5587.
42. Tang, L.; Wang, H.; Li, L.; Yang, K.; Mi, Z. Quantitative models in emission trading system research: a literature review. Renew. Sust. Energ. Rev. 2020, 132, 110052.
43. Forrester, J. W. Industrial dynamics: a major breakthrough for decision makers. In: Klaus P, Müller S, editors. The roots of logistics. Berlin: Springer Berlin Heidelberg; 2012. pp. 141-72.
44. Liu, D.; Zhao, W.; Li, Z.; Xu, X.; Xiao, B.; Niu, D. Can hydropower develop as expected in China? A scenario analysis based on system dynamics model. Energy 2018, 161, 118-29.
45. Liu, D.; Xiao, B. Exploring the development of electric vehicles under policy incentives: a scenario-based system dynamics model. Energy. Policy. 2018, 120, 8-23.
46. Lin, C.; Li, X. Carbon peak prediction and emission reduction pathways exploration for provincial residential buildings: evidence from Fujian Province. Sustainable. Cities. Soc. 2024, 102, 105239.
47. Liu, X.; Mao, G.; Ren, J.; Li, R. Y. M.; Guo, J.; Zhang, L. How might China achieve its 2020 emissions target? A scenario analysis of energy consumption and CO2 emissions using the system dynamics model. J. Clean. Prod. 2015, 103, 401-10.
48. Zhang, J.; Wang, Z.; Tang, L.; et al. The simulation of carbon emission trading system in Beijing-Tianjin-Hebei Region: an analysis based on system dynamics. Chin. J. Manag. Sci. 2016, 24, 1-8. (in Chinese).
49. Chi, Y.; Zhao, H.; Hu, Y.; Yuan, Y.; Pang, Y. The impact of allocation methods on carbon emission trading under electricity marketization reform in China: a system dynamics analysis. Energy 2022, 259, 125034.
50. Liu, X.; Bagchi, T.; Sy, C. L.; Gao, H. O. A blockchain-based carbon registry platform for credible climate action in transportation. npj. Clim. Action. 2026, 5, 342.
51. Yuan, X.; Xi, J.; Li, C.; et al. A study on carbon emission peak forecast and emission reduction potential of China’s industrial sector. J. Stat. Inf. 2020, 35, 72-82. (in Chinese).
52. Shan, Y.; Huang, Q.; Guan, D.; Hubacek, K. China CO2 emission accounts 2016-2017. Sci. Data. 2020, 7, 54.
53. Lin, B.; Jia, Z. Impacts of carbon price level in carbon emission trading market. Appl. Energy. 2019, 239, 157-70.
54. Sterman, J.D. System Dynamics: systems thinking and modeling for a complex world. Working Paper, Massachusetts Institute of Technology, Engineering Systems Division: Cambridge, MA, 2002. Available from: http://hdl.handle.net/1721.1/102741 (accessed 2026-10-26).
55. Hao, J.; Yuan, H.; Liu, J.; Chin, C. S.; Lu, W. A model for assessing the economic performance of construction waste reduction. J. Clean. Prod. 2019, 232, 427-40.
56. Yang, L.; Li, Z. Technology advance and the carbon dioxide emission in China - empirical research based on the rebound effect. Energy. Policy. 2017, 101, 150-61.
57. Wang, X.; Li, P.; Yuan, Y.; Zhang, Q. The impact of the carbon trading market on corporate employment: theoretical and empirical evidence. Energy 2025, 320, 135098.
58. Wang, Y.; Liu, J.; Tang, X.; Wang, Y.; An, H.; Yi, H. Decarbonization pathways of China’s iron and steel industry toward carbon neutrality. Resour. Conserv. Recy. 2023, 194, 106994.
59. Shan, Y.; Zhou, Y.; Meng, J.; Mi, Z.; Liu, J.; Guan, D. Peak cement-related CO2 emissions and the changes in drivers in China. J. Ind. Ecol. 2019, 23, 959-71.
60. Wu, T.; Ng, S. T.; Chen, J. Deciphering the CO2 emissions and emission intensity of cement sector in China through decomposition analysis. J. Clean. Prod. 2022, 352, 131627.
61. Li, J.; Yao, Y.; Wang, X. The first compliance cycle of China’s National Emissions trading scheme: insights and implications. Carb. Neutrality. 2022, 1, 35.
62. Gan, T.; Zhou, Z.; Li, S.; Tu, Z. Carbon emission trading, technological progress, synergetic control of environmental pollution and carbon emissions in China. J. Clean. Prod. 2024, 442, 141059.
63. Li, Y.; Zhao, J. The effectiveness of carbon emission trading system: evidence from China’s regional markets. J. Dev. Econ. 2026, 179, 103631.
64. Chen, Z.; Song, P.; Wang, B. Carbon emissions trading scheme, energy efficiency and rebound effect - evidence from China’s provincial data. Energy. Policy. 2021, 157, 112507.
65. Huang, L.; Zhu, B.; Wang, P.; Jiang, M. Impacts of price regulation on the efficiency and stability in carbon market. J. Manag. Sci. China. 2026, 29, 17-31. (in Chinese).
Cite This Article
 Open Access
How to Cite
Zhu, T.; Zeng, A.; Zhu, K.; Guo, Z. Coupling compliance and voluntary carbon markets: a system dynamics assessment in China. Carbon Footprints 2026, 5, 57. https://dx.doi.org/10.20517/cf.2026.113
Download Citation
If you have the appropriate software installed, you can download article citation data to the citation manager of your choice. Simply select your manager software from the list below and click on download.
Export Citation File
Type of Import
Tips on Downloading Citation
Citation Manager File Format
Type of Import
Direct Import: When the Direct Import option is selected (the default state), a dialogue box will give you the option to Save or Open the downloaded citation data. Choosing Open will either launch your citation manager or give you a choice of applications with which to use the metadata. The Save option saves the file locally for later use.
Indirect Import: When the Indirect Import option is selected, the metadata is displayed and may be copied and pasted as needed.
About This Article
Copyright

Data & Comments
Data
0






Comments
Comments must be written in English. Spam, offensive content, impersonation, and private information will not be permitted. If any comment is reported and identified as inappropriate content by OAE staff, the comment will be removed without notice. If you have any queries or need any help, please contact us at [email protected].